Sales Ledger Control Accounts
Sales ledger control accounts
Sales ledger control accounts
Where do I find the information to complete a sales ledger control account?
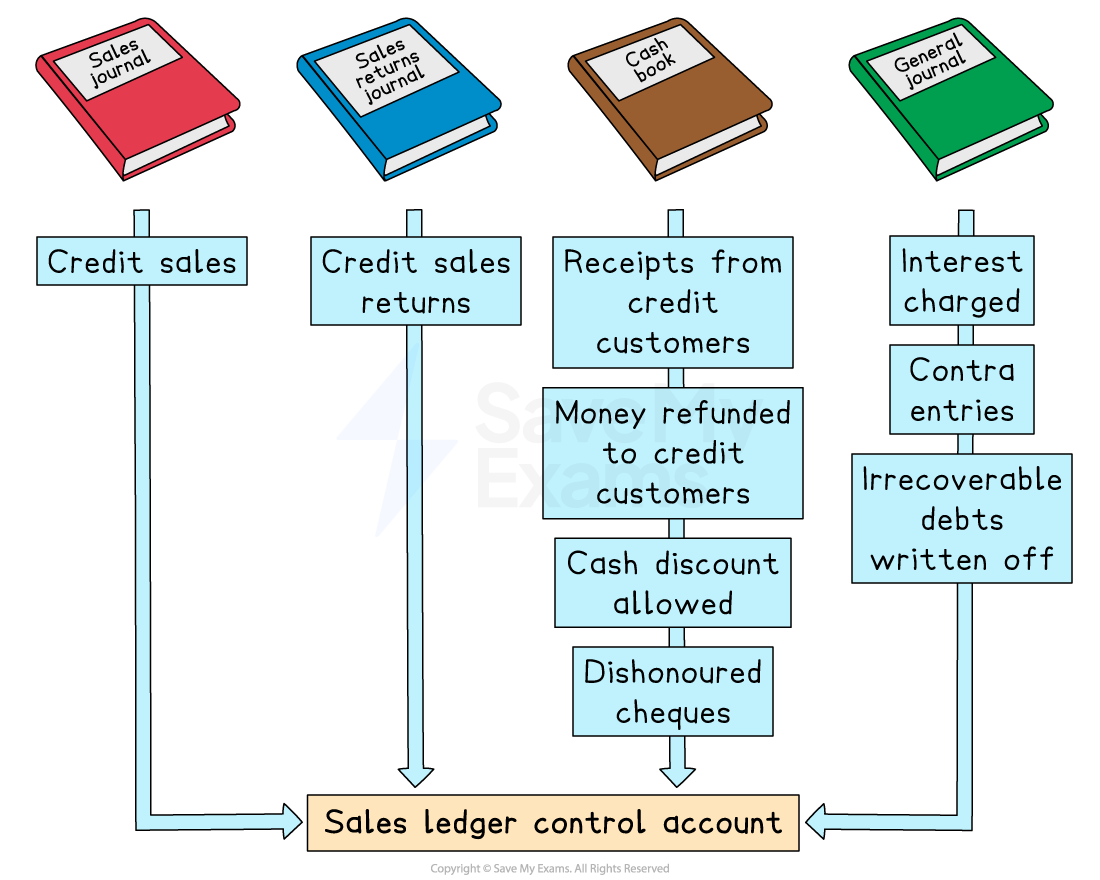
The books of prime entry are used to find the totals
The sales journal is used to find the total value of credit sales
The sales returns journal is used to find the total value of returned goods
The cash book is used to find the total values for:
Money received from credit customers
Money refunded to credit customers
Cash discounts allowed to credit customers
Dishonoured cheques received from credit customers
The journal is used to find the total values for:
Interest charged to credit customers on overdue accounts
Contra entries against the purchases ledger
Irrecoverable debts written off
Why might there be a credit balance in a sales ledger control account?
A trade receivables account will usually have a debit balance
This indicates that the credit customer owes the business money
However, a trade receivables account could have a credit balance
This indicates that the credit customer is owed money
Credit balances can occur when:
Credit customers pay in advance of buying goods
Credit customers make an overpayment
The business owes refunds to credit customers
The customers have paid for goods and then returned them
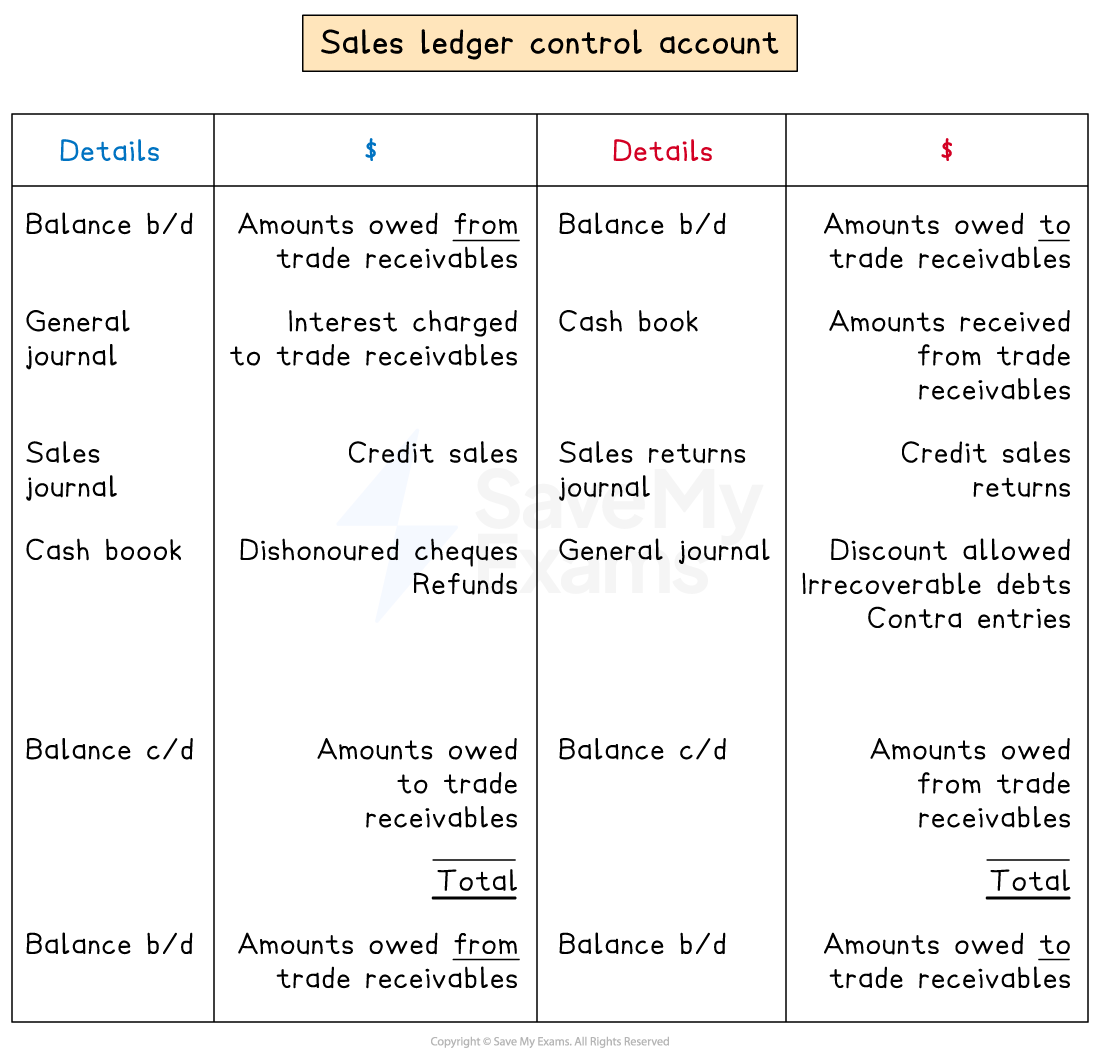
Debit and credit balances are totalled separately in the sales ledger control account
This means there could be two opening balances and two closing balances
What is the layout of a sales ledger control account?
The layout looks very similar to the layout of a trade receivables ledger account
The main differences are:
There could be two opening balances
There could be two closing balances
Entries on the debit side: | Entries on the credit side: |
|---|---|
|
|