The Trial Balance
Uses & Limitations of a Trial Balance
Uses & limitations of a trial balance
What is a trial balance?
A trial balance is a statement which lists all accounts and their balances on a particular date
Each balance is placed either in the debit column or in the credit column
The totals of the debit and credit columns are calculated
The totals should be equal
A trial balance is not part of the double entry system
The balance for the inventory account will always be the opening balance
This is because the current inventory is contained within the purchases account
This is dealt with once the balances are transferred to the income statement
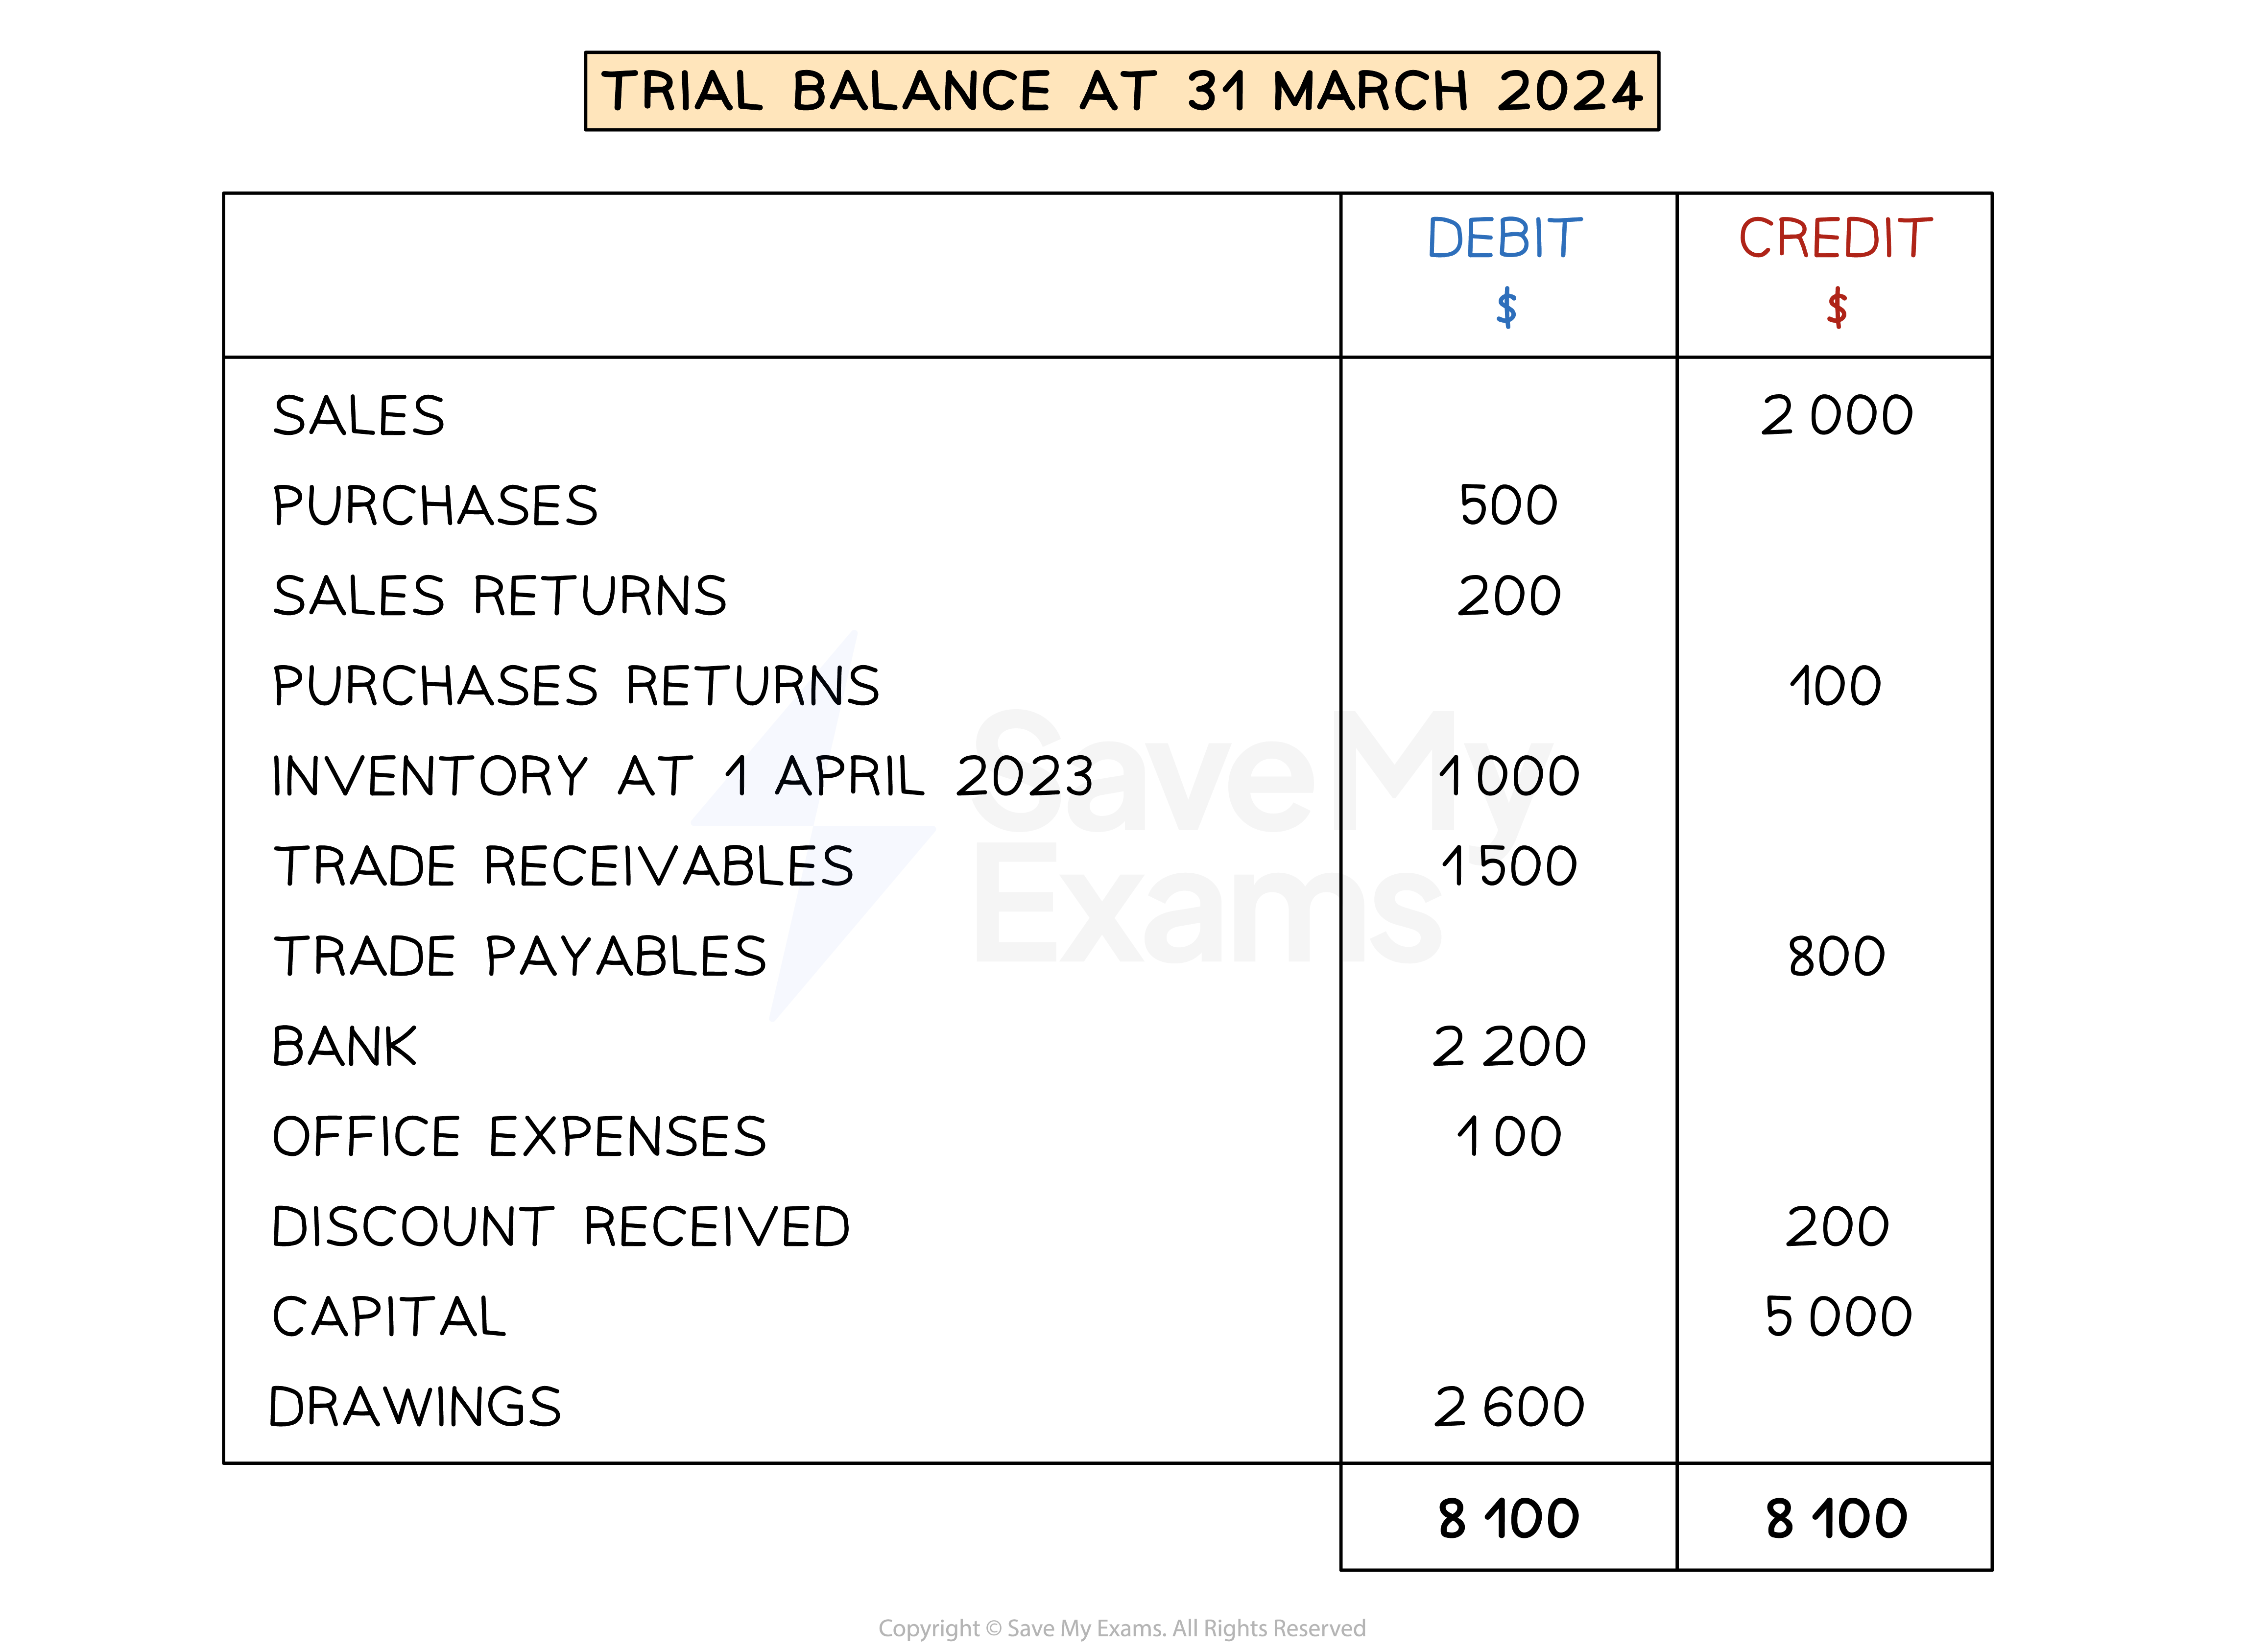
What are the uses of a trial balance?
A trial balance is used to check for arithmetic errors in the ledger accounts
If the balance of a ledger account has been miscalculated, it is likely that the totals in the trial balance will not be equal
Preparing a trial balance helps with the preparation of financial statements
All the balances are in one place
What are the limitations of a trial balance?
Not all errors are identified by a trial balance
The totals may be equal despite there being errors
You will need to use other measures to locate errors
Such as bank reconciliation statements and control accounts
Preparing a Trial Balance
Preparing a trial balance
How do I prepare a trial balance?
You will likely be given a list of accounts and balances
STEP 1
Identify whether each account should have a debit or a credit balanceThe table below gives a summary of the different accounts
STEP 2
Check that the total of the debits is equal to the total of the creditsSTEP 3
Write each account in the trial balance and put the balance in the correct columnSTEP 4
Total each column
Accounts with debit balances | Accounts with credit balances |
Purchases | Purchases returns (returns outwards) |
Sales returns (returns inwards) | Sales (revenue) |
Other expenses | Other income |
Trade receivables | Trade payables |
Bank | Bank overdraft |
Other assets (Including inventory, vehicles, machinery, etc) | Other liabilities (Including bank loan, mortgage, etc) |
Drawings | Capital |
Provision for depreciation | |
Provision for doubtful debt |
How do I amend a trial balance?
You could be given a trial balance which contains errors
The balances could also be in the wrong columns
STEP 1
Correct the errors to find the correct balances for each accountSTEP 2
Double-check whether each account has been correctly identified as a debit or a creditSTEP 3
Complete a corrected trial balanceThe totals will be equal