Business Documents for Credit Transactions
Invoices
Invoices
What is an invoice?
An invoice is used as a record of a credit sale or credit purchase
The supplier issues an invoice to the credit customer
The customer might refer to this as a purchases invoice
The supplier will keep a copy
They might refer to it as a sales invoice
An entry is made in the books of prime entry when an invoice is issued or received for goods or services
The customer enters the value in the purchases journal
The supplier enters the value in the sales journal
If the invoice is for a non-current asset then the book of original entry is the journal
What information is contained in an invoice?
The date of the transaction
The details of the supplier
Name and address
The details of the customer
Name and address
The details of the goods or services
The quantity
The price of each item
Trade discount
This is deducted before the total amount is stated
The total amount owed
Terms for eligibility of cash discount
Date payment is required by
It might also state any interest or charges that will be applied after this date
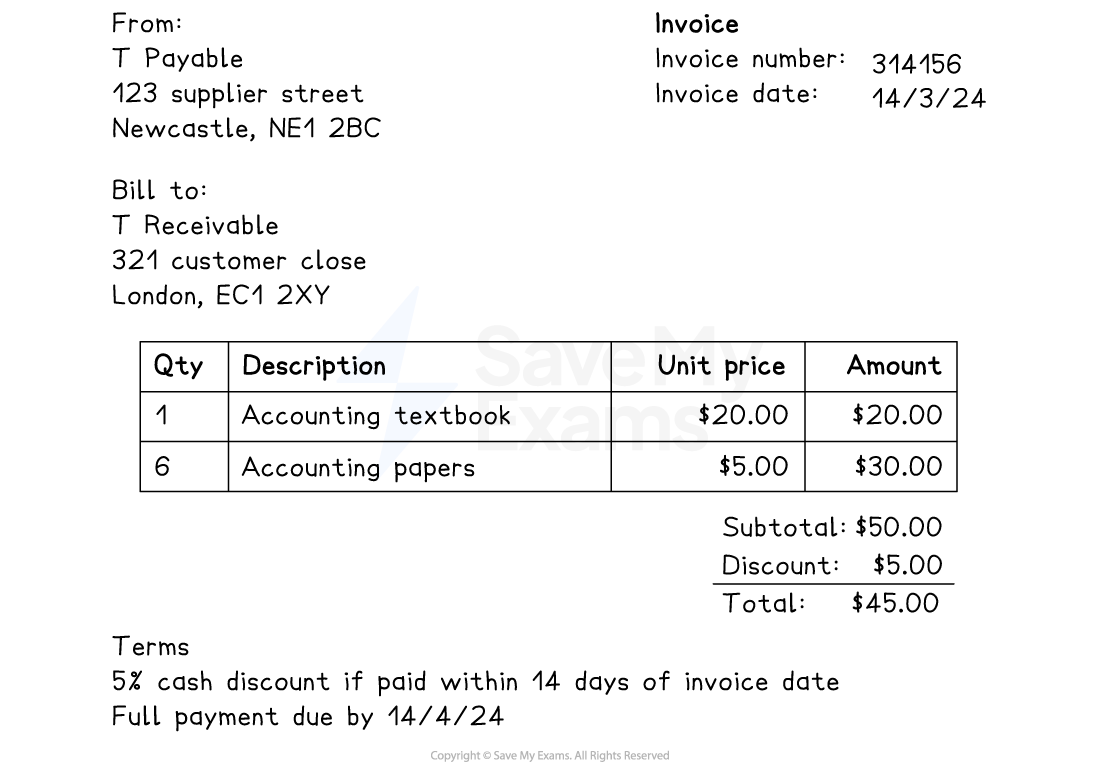
Debit notes & credit notes
Debit notes & credit notes
What is a debit note?
A credit customer issues a debit note to a supplier to request a reduction in the balance of an invoice
The customer could ask for a reduction if
The goods are damaged or faulty
They were sent the wrong items
Goods are missing from their order
No entries are recorded in the books of prime entry at this stage
This is because the supplier has not yet authorised the reduction
This is done when the customer receives a credit note from the supplier
What information is contained in a debit note?
The date of the request
The details of the supplier
Name and address
The details of the customer
Name and address
The reason for the request for a reduction
Details of the goods that are being returned
Details of the goods that were missing
The total reduction that is being requested
What is a credit note?
A supplier issues a credit note to a credit customer when the balance on an invoice is reduced
The customer uses the credit note received to record the return
It will be matched and filed with the corresponding invoice and debit note
The supplier keeps a copy of the credit note issued to record the return
It will be matched and filed with the corresponding invoice
An entry is made in the books of prime entry when a credit note is issued or received
The customer enters the value in the purchases returns journal
The supplier enters the value in the sales returns journal
What information is contained in a credit note?
The date of the reduction
The details of the supplier
Name and address
The details of the customer
Name and address
The reason for the reduction
Details of the goods that are being returned
Details of the goods that were missing
The total reduction that is being given
Statements of account
Statements of account
What is a statement of account?
A statement of account is used to show all transactions between a credit customer and a supplier within a given time frame
A statement of account is issued on a regular basis by the supplier
No entries are recorded in the books of prime entry when a statement of account is issued or received
This is because no new transactions have taken place
The customer can check the balance on the statement with the balance in their purchases ledger account
There is usually a balance column which shows the balance after each transaction
The statement of account is written from the point of view of the supplier
Transactions which increase the customer’s balance will be labelled as a debit
Transactions which decrease the customer’s balance will be labelled as a credit
What information is contained in a statement of account?
The date that the statement is issued
The details of the supplier
Name and address
The details of the customer
Name and address
The opening balance
The date and amount of any purchases by the customer
These will correspond to invoices that were issued
The date and amount of any returns by the customer
These will correspond to credit notes that were issued
Payments made by the customer
Cash discounts received by the customer
The closing balance