Income & Expenditure Account
Income & expenditure accounts
Income & expenditure accounts
What is an income and expenditure account?
An income and expenditure account is a statement that calculates the surplus or deficit
A surplus is comparable to a profit for a business
A deficit is comparable to a loss for a business
Clubs and societies do not operate to make a profit so the terms profit and loss are not used
The total expenses are subtracted from the income
If the income is greater than the expenses then there is a surplus
If the income is less than the expenses then there is a deficit
The income and expenditure account is similar to an income statement of a business
Only expenses and income are included
Assets and liabilities are not included
Adjustments are made for:
Depreciation of non-current assets
Accruals and prepayments of expenses and income
Any subscriptions which are written off
What are the differences between a receipts and payments account and an income and expenditure account?
The differences are summarised in the total
Receipts and payments account | Income and expenditure account |
|---|---|
Includes only money that is received or paid | Includes only income and expenses |
Includes only transactions involving money | Includes transactions involving non-monetary items such as depreciation |
Includes both capital and revenue receipts and expenditure | Includes only revenue receipts and expenditure |
Does not include adjustments for accruals or prepayments of expenses and income | Includes adjustments for accruals or prepayments of expenses and income |
The closing balance represents the bank balance or amount of cash | The final amount represents the surplus or deficit |
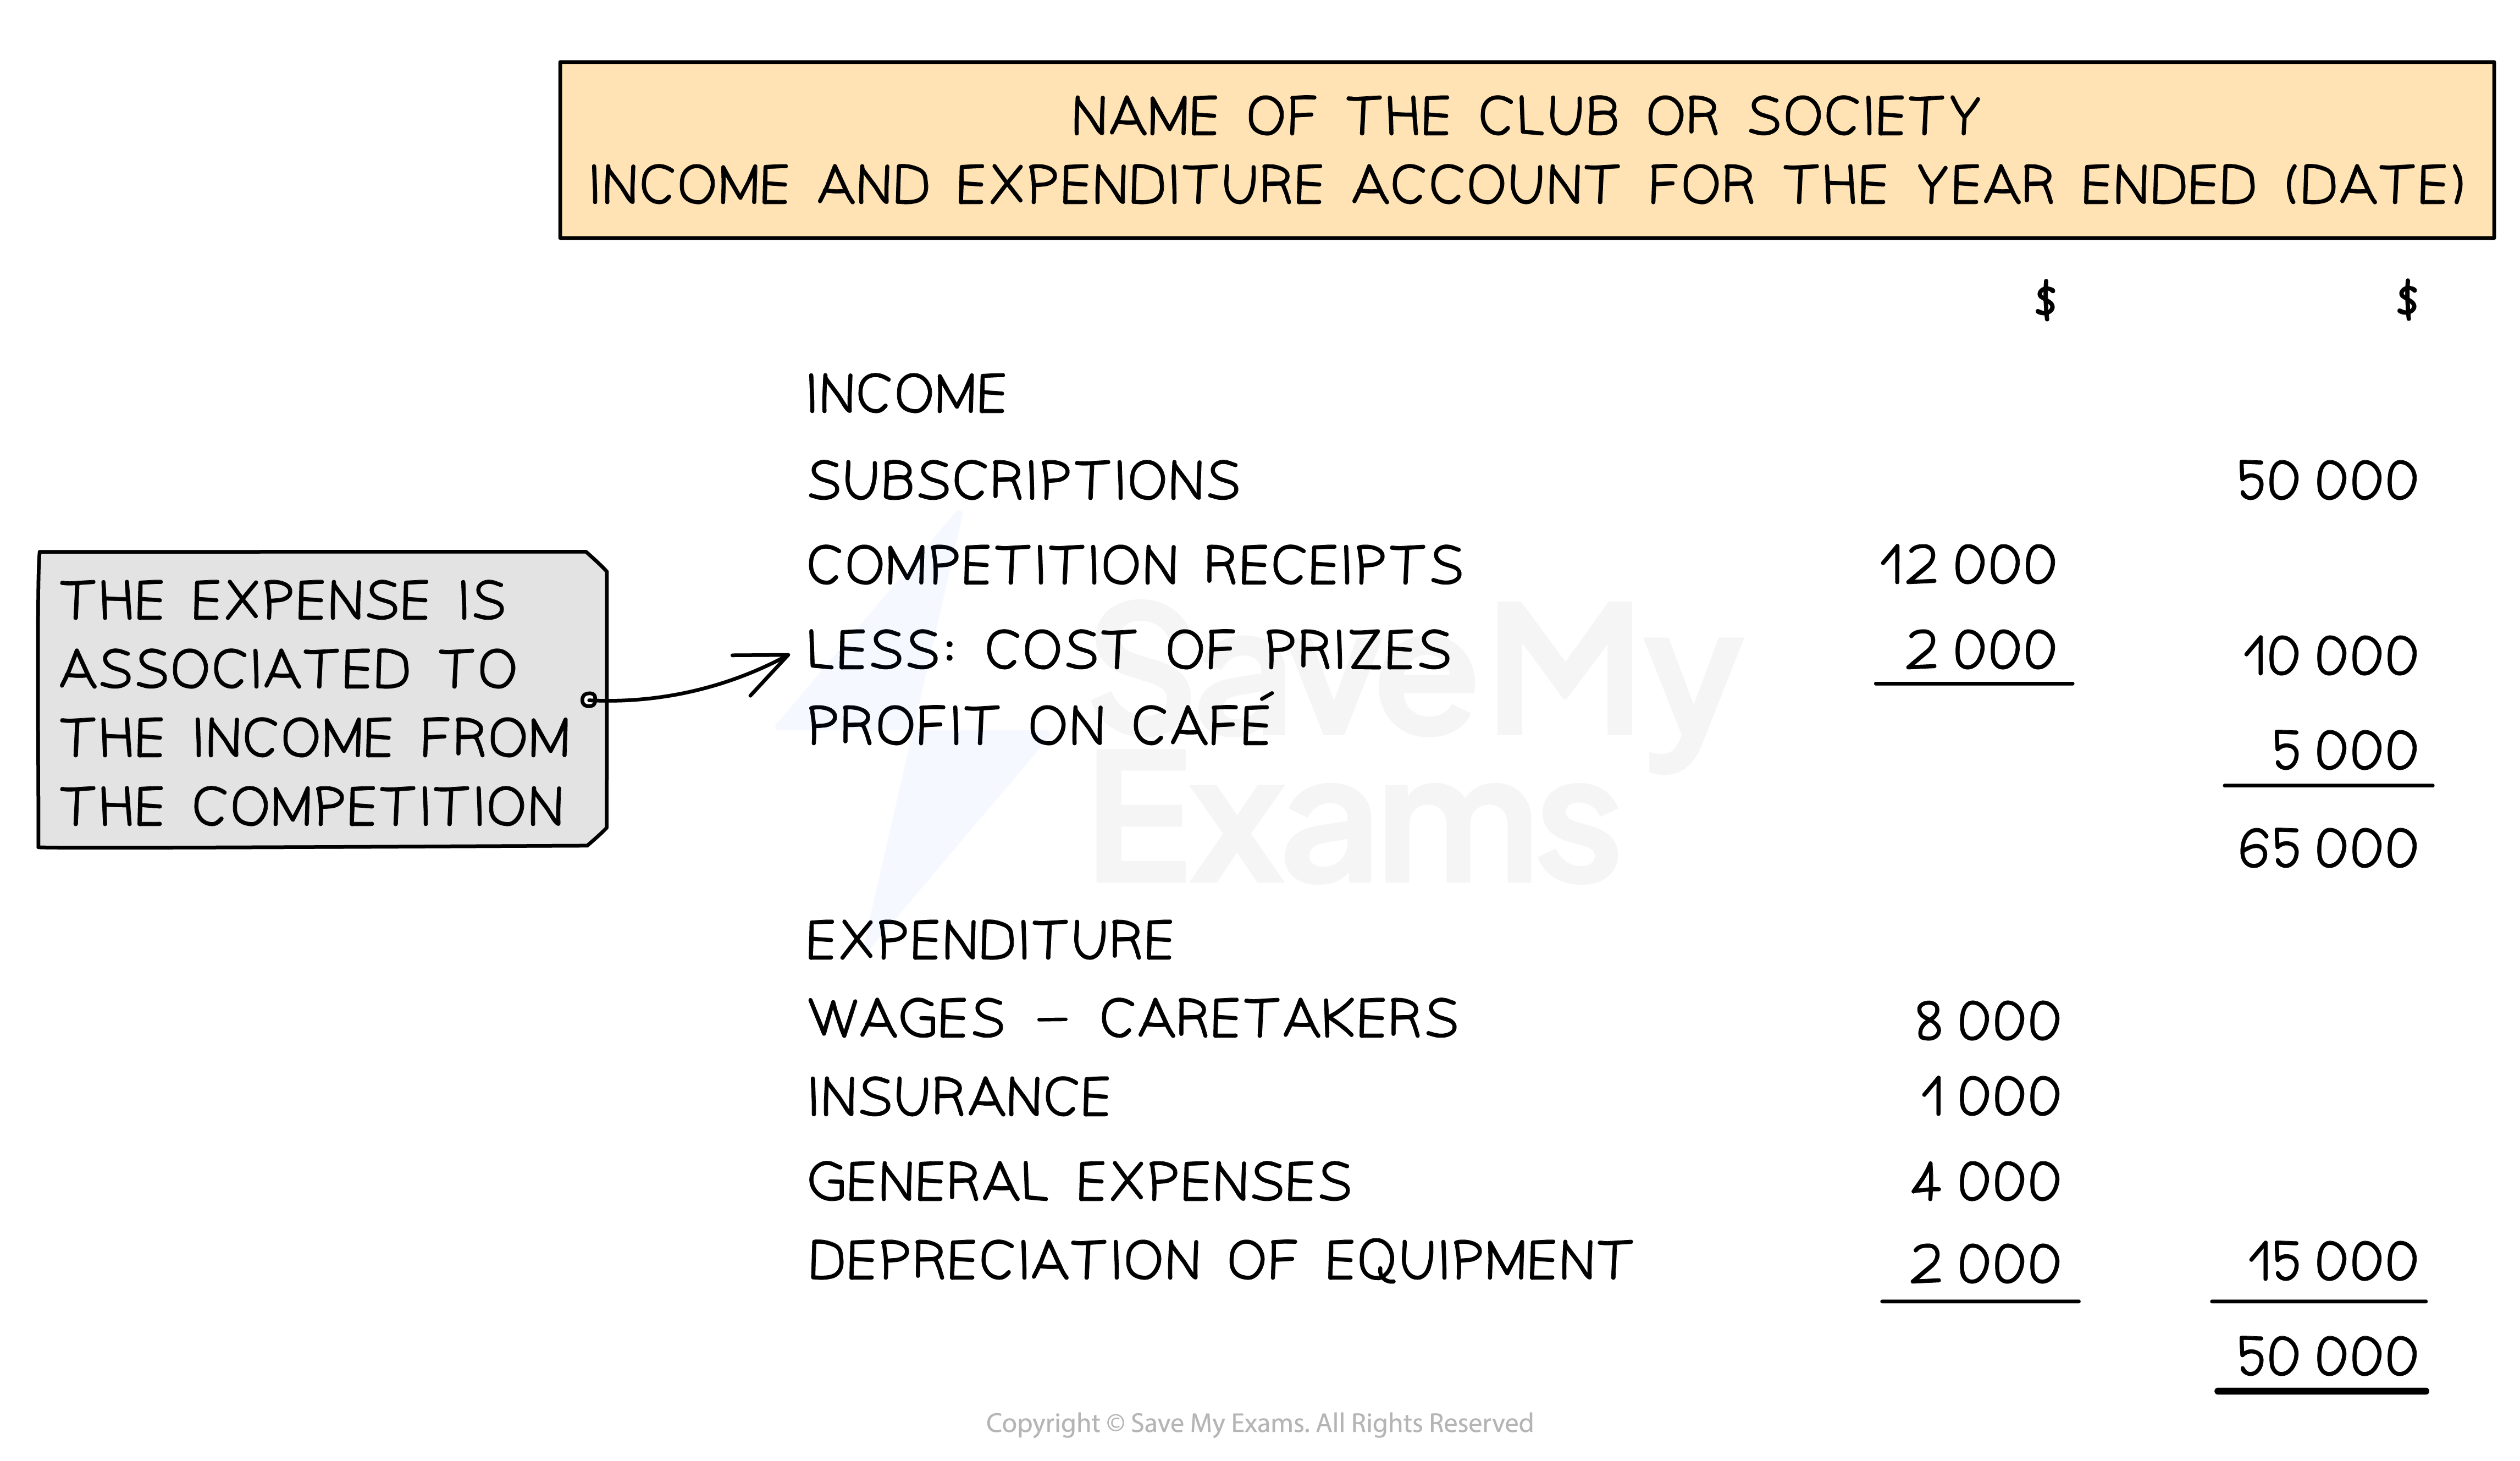
What is the layout of an income and expenditure account?
The account is prepared in a similar way as the profit section of the income statement for other types of businesses
Deal with any adjustments
Accruals
Subtract accruals from the previous year
Add accruals at the end of the current year
Prepayments
Add prepayments from the previous year
Subtract prepayments at the end of the current year
Calculate any depreciation charges
List the income first
If there are any associated costs with a source of income then these should be subtracted in this section
For example, income from a competition should subtract the cost of the competition's prizes
Include any profits calculated on the income statements for any trading activities
List the expenditure next
Include any losses calculated on the income statements for any trading activities
Do not include expenses related to specific trading activities
These will be included in the income statements for those activities and will contribute to the profit or loss
Find the surplus or deficit of the year by subtracting the two totals