Statement of Changes in Equity
Statements of changes in equity
Statements of changes in equity
What is a statement of changes in equity?
A statement of changes in equity is a statement showing how the equity of a limited company has changed over a year
It shows the changes to:
The ordinary share capital
The non-redeemable preference share capital
The retained earnings
The general reserve
It shows how the profits are used
Some of the profits will be distributed to the shareholders as dividends
The remaining profits are carried forward to the next financial year as retained earnings
Some of the retained earnings might be transferred to the general reserve
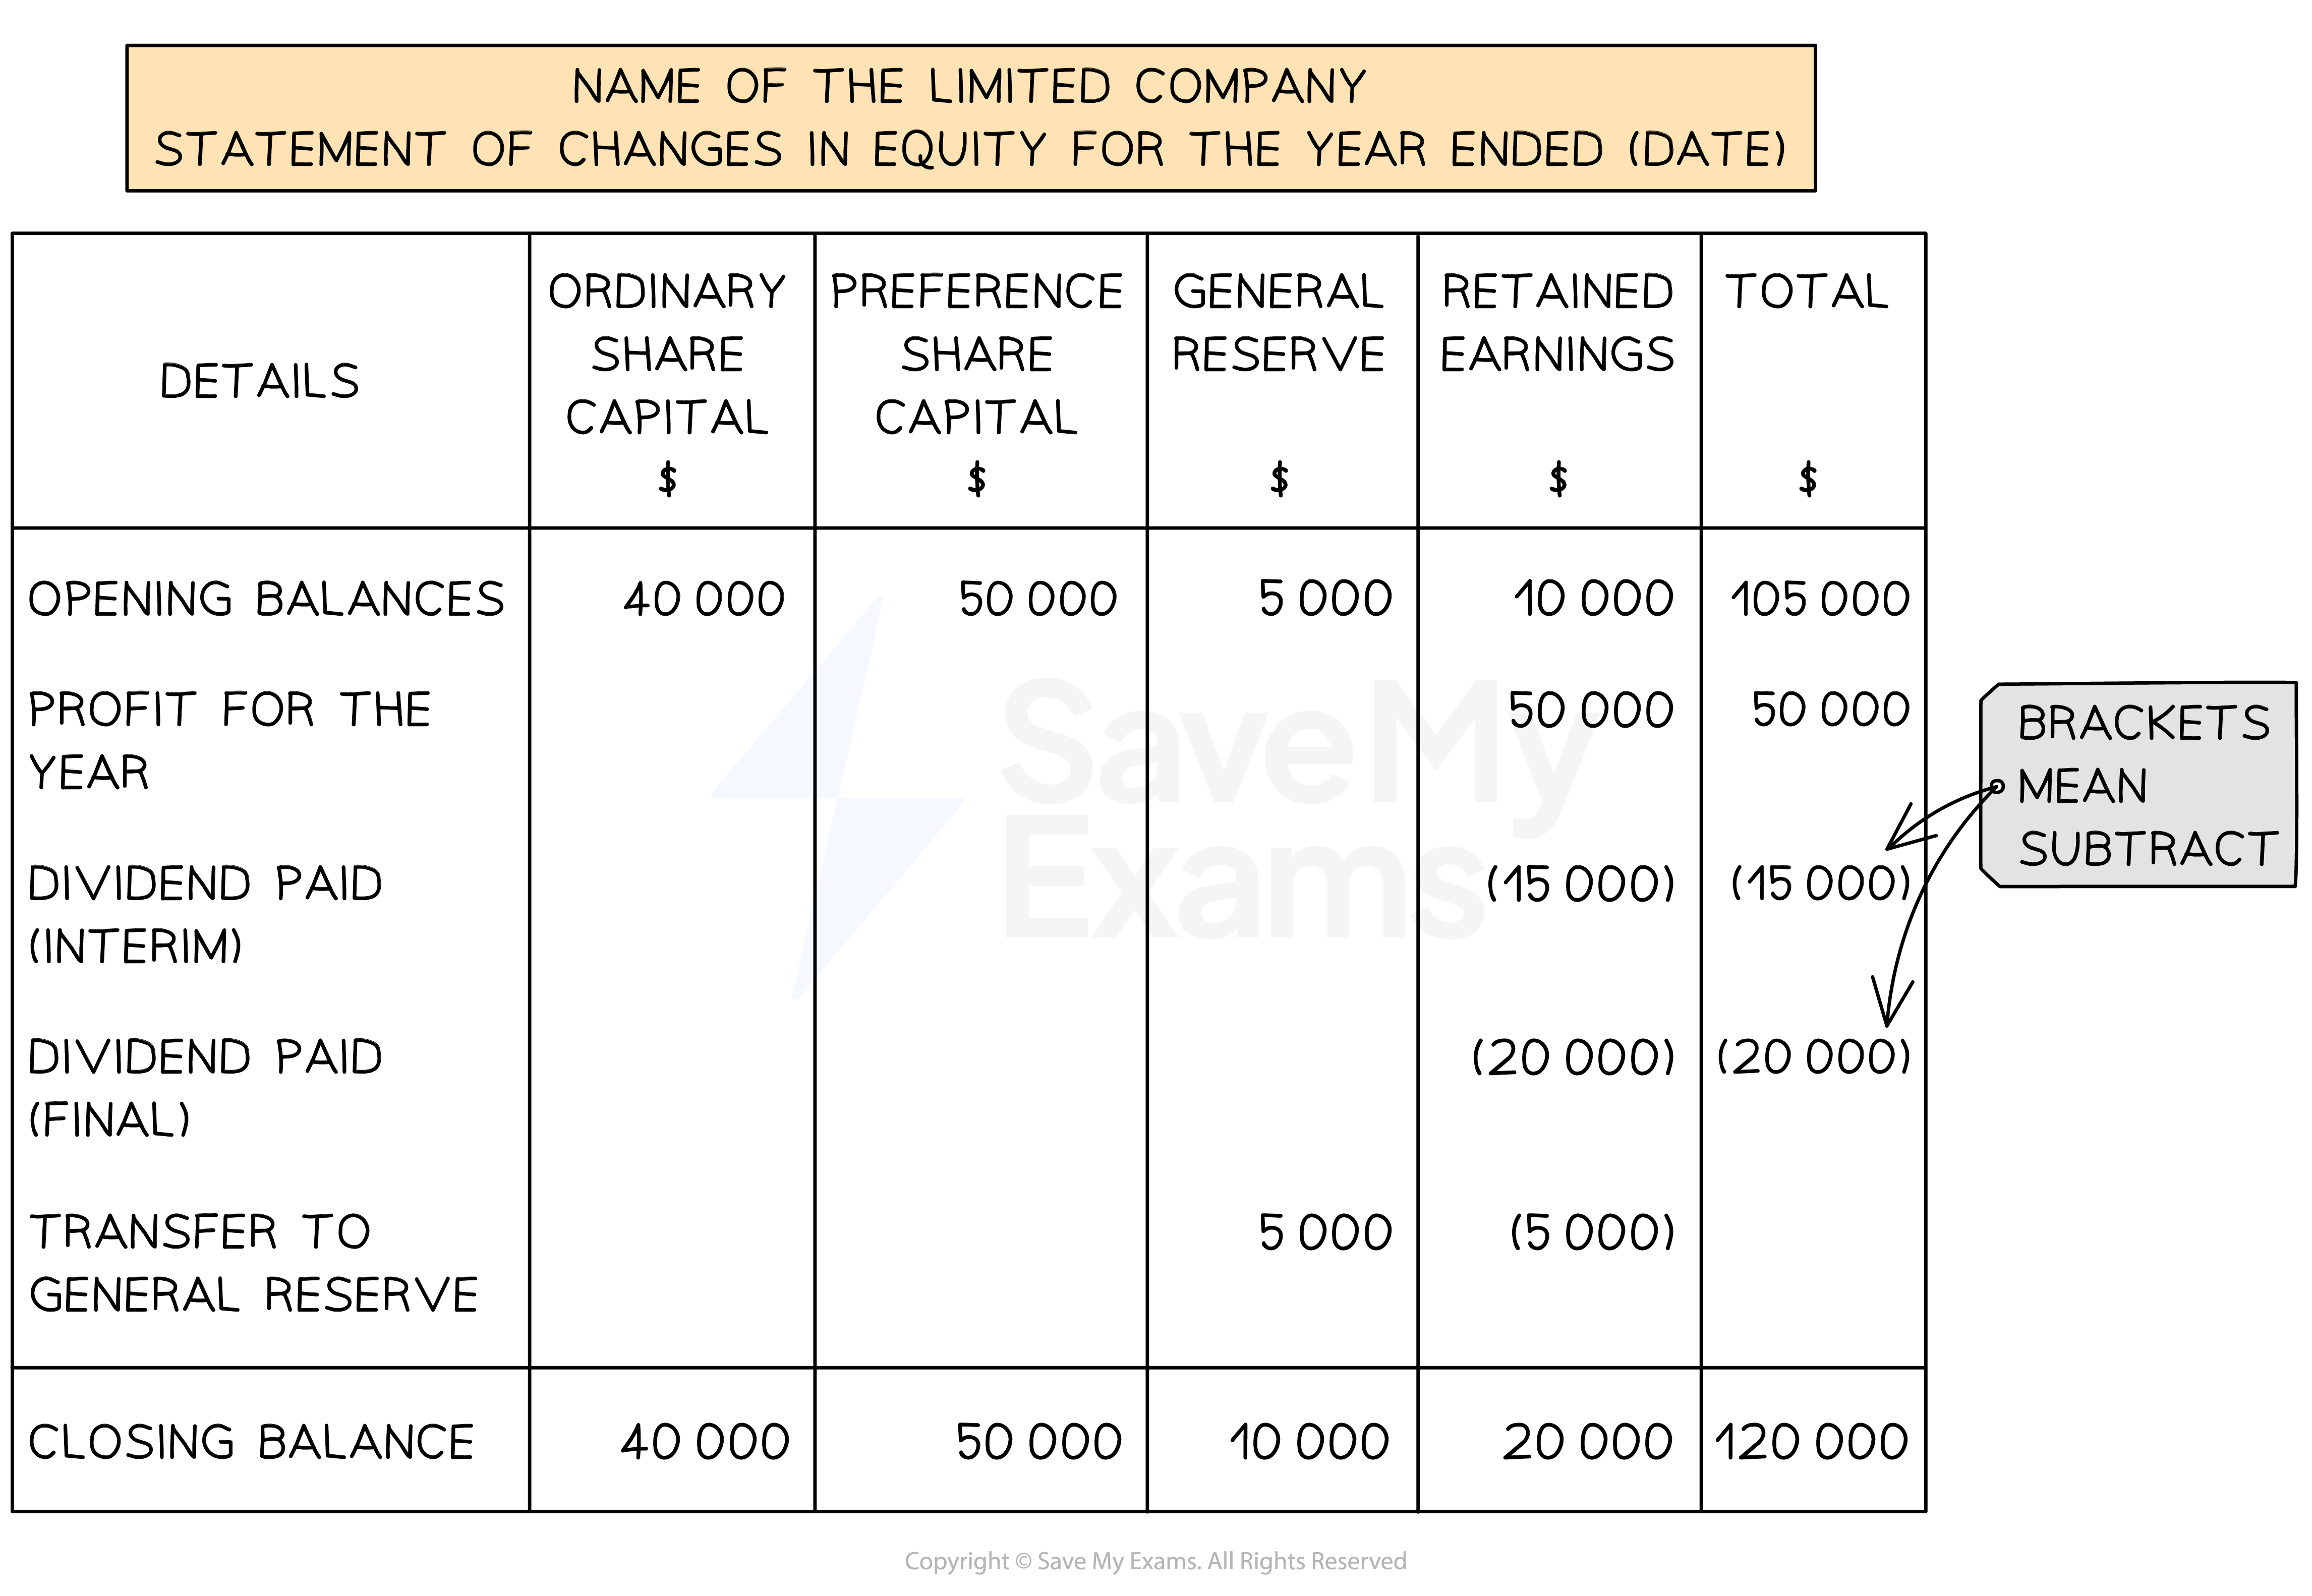
What are the reasons for the changes in the value of the total equity?
The equity of the limited company is likely to change due to the following
The profit for the year is added to the retained earnings
The profit is distributed or paid to shareholders in the form of interim and final dividends
Some of the profit for the year is transferred to the general reserve
How are dividends treated on the statement of changes in equity?
Shareholders get a share or portion of the profits as dividends
The statement of changes in equity shows the dividends paid to shareholders during the year for any ordinary shares and non-redeemable preference shares
Dividends that are paid halfway through the year are known as interim dividends
Dividends that are paid at the end of the year are known as final dividends
Dividends proposed by the directors to be paid are not to be included in the statement of changes in equity until the amount is paid
Are redeemable preference shares included on the statement of changes in equity?
No information about redeemable preference shares is stated on the statement of changes in equity
They are a liability so they are included on the statement of financial position
Payment of their dividends is a finance cost and is included on the income statement