Income Statement
Income statement for sole traders
Income statement for sole traders
What is the purpose of an income statement for a sole trader?
It is a statement prepared for a trading period to show the gross profit and the profit for the year
A financial year does not necessarily follow the calendar year from January to December
For example, if a business commences trading on 1 July 2023 then the first financial year would run from 1 July 2023 to 30 June 2024
The income statement consists of two parts
The trading section shows the calculation of the gross profit
The profit and loss section shows the calculation of the profit for the year
The income statement is part of the double entry system of book-keeping
Debit entries to the income statement decrease profit
These are usually the expenses
Credit entries to the income statement increase profit
These are usually the sources of income
An income statement can sometimes be created like an account with a debit side and a credit side
This is called the horizontal format
The balancing figure will be the profit or loss
Profit if it is on the debit side
Loss if it is on the credit side
However, most businesses produce income statements as a statement using the vertical format
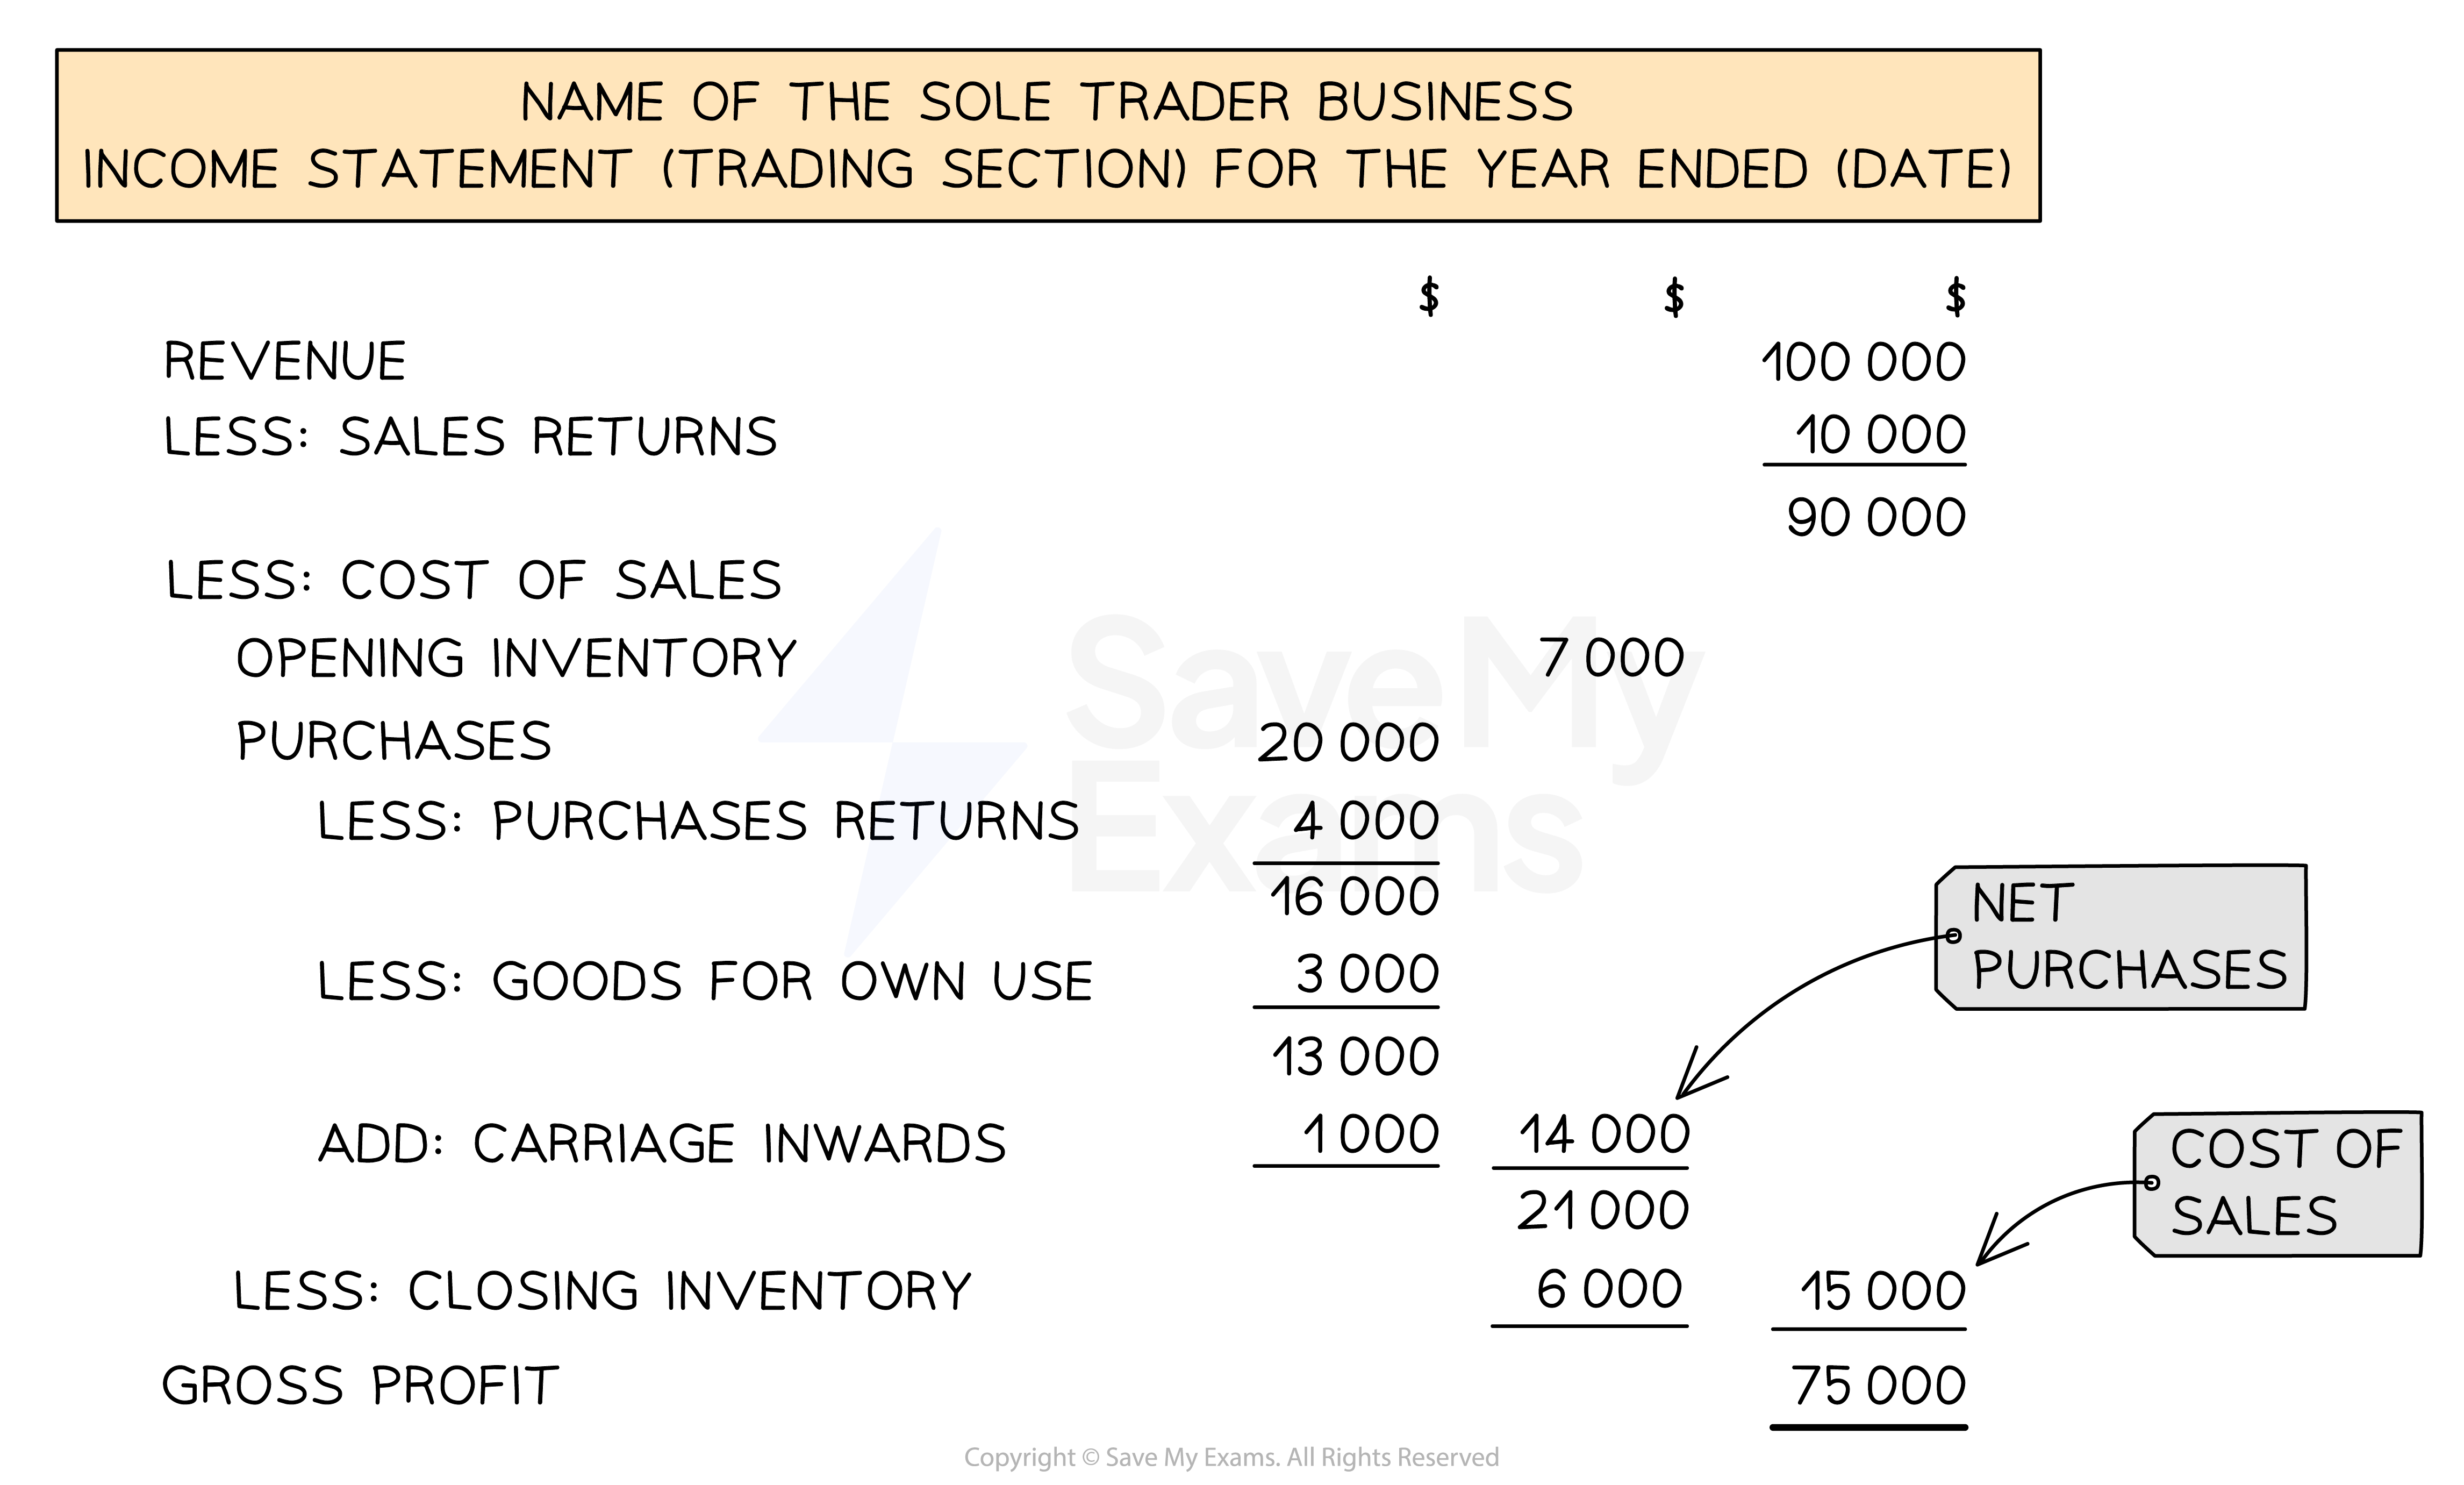
How do I complete the trading section of an income statement?
STEP 1
Calculate the total revenue and put the value in the far right columnRevenue
Less sales returns
STEP 2
Calculate the cost of sales and put the value in the far right columnOpening inventory
Add net purchases
Purchases
Less purchases returns
Less goods for own use
Add carriage inwards
Less closing inventory
STEP 3
Calculate the gross profit and put the value in the far right columnRevenue
Less cost of sales
How do I complete the profit and loss section of an income statement?
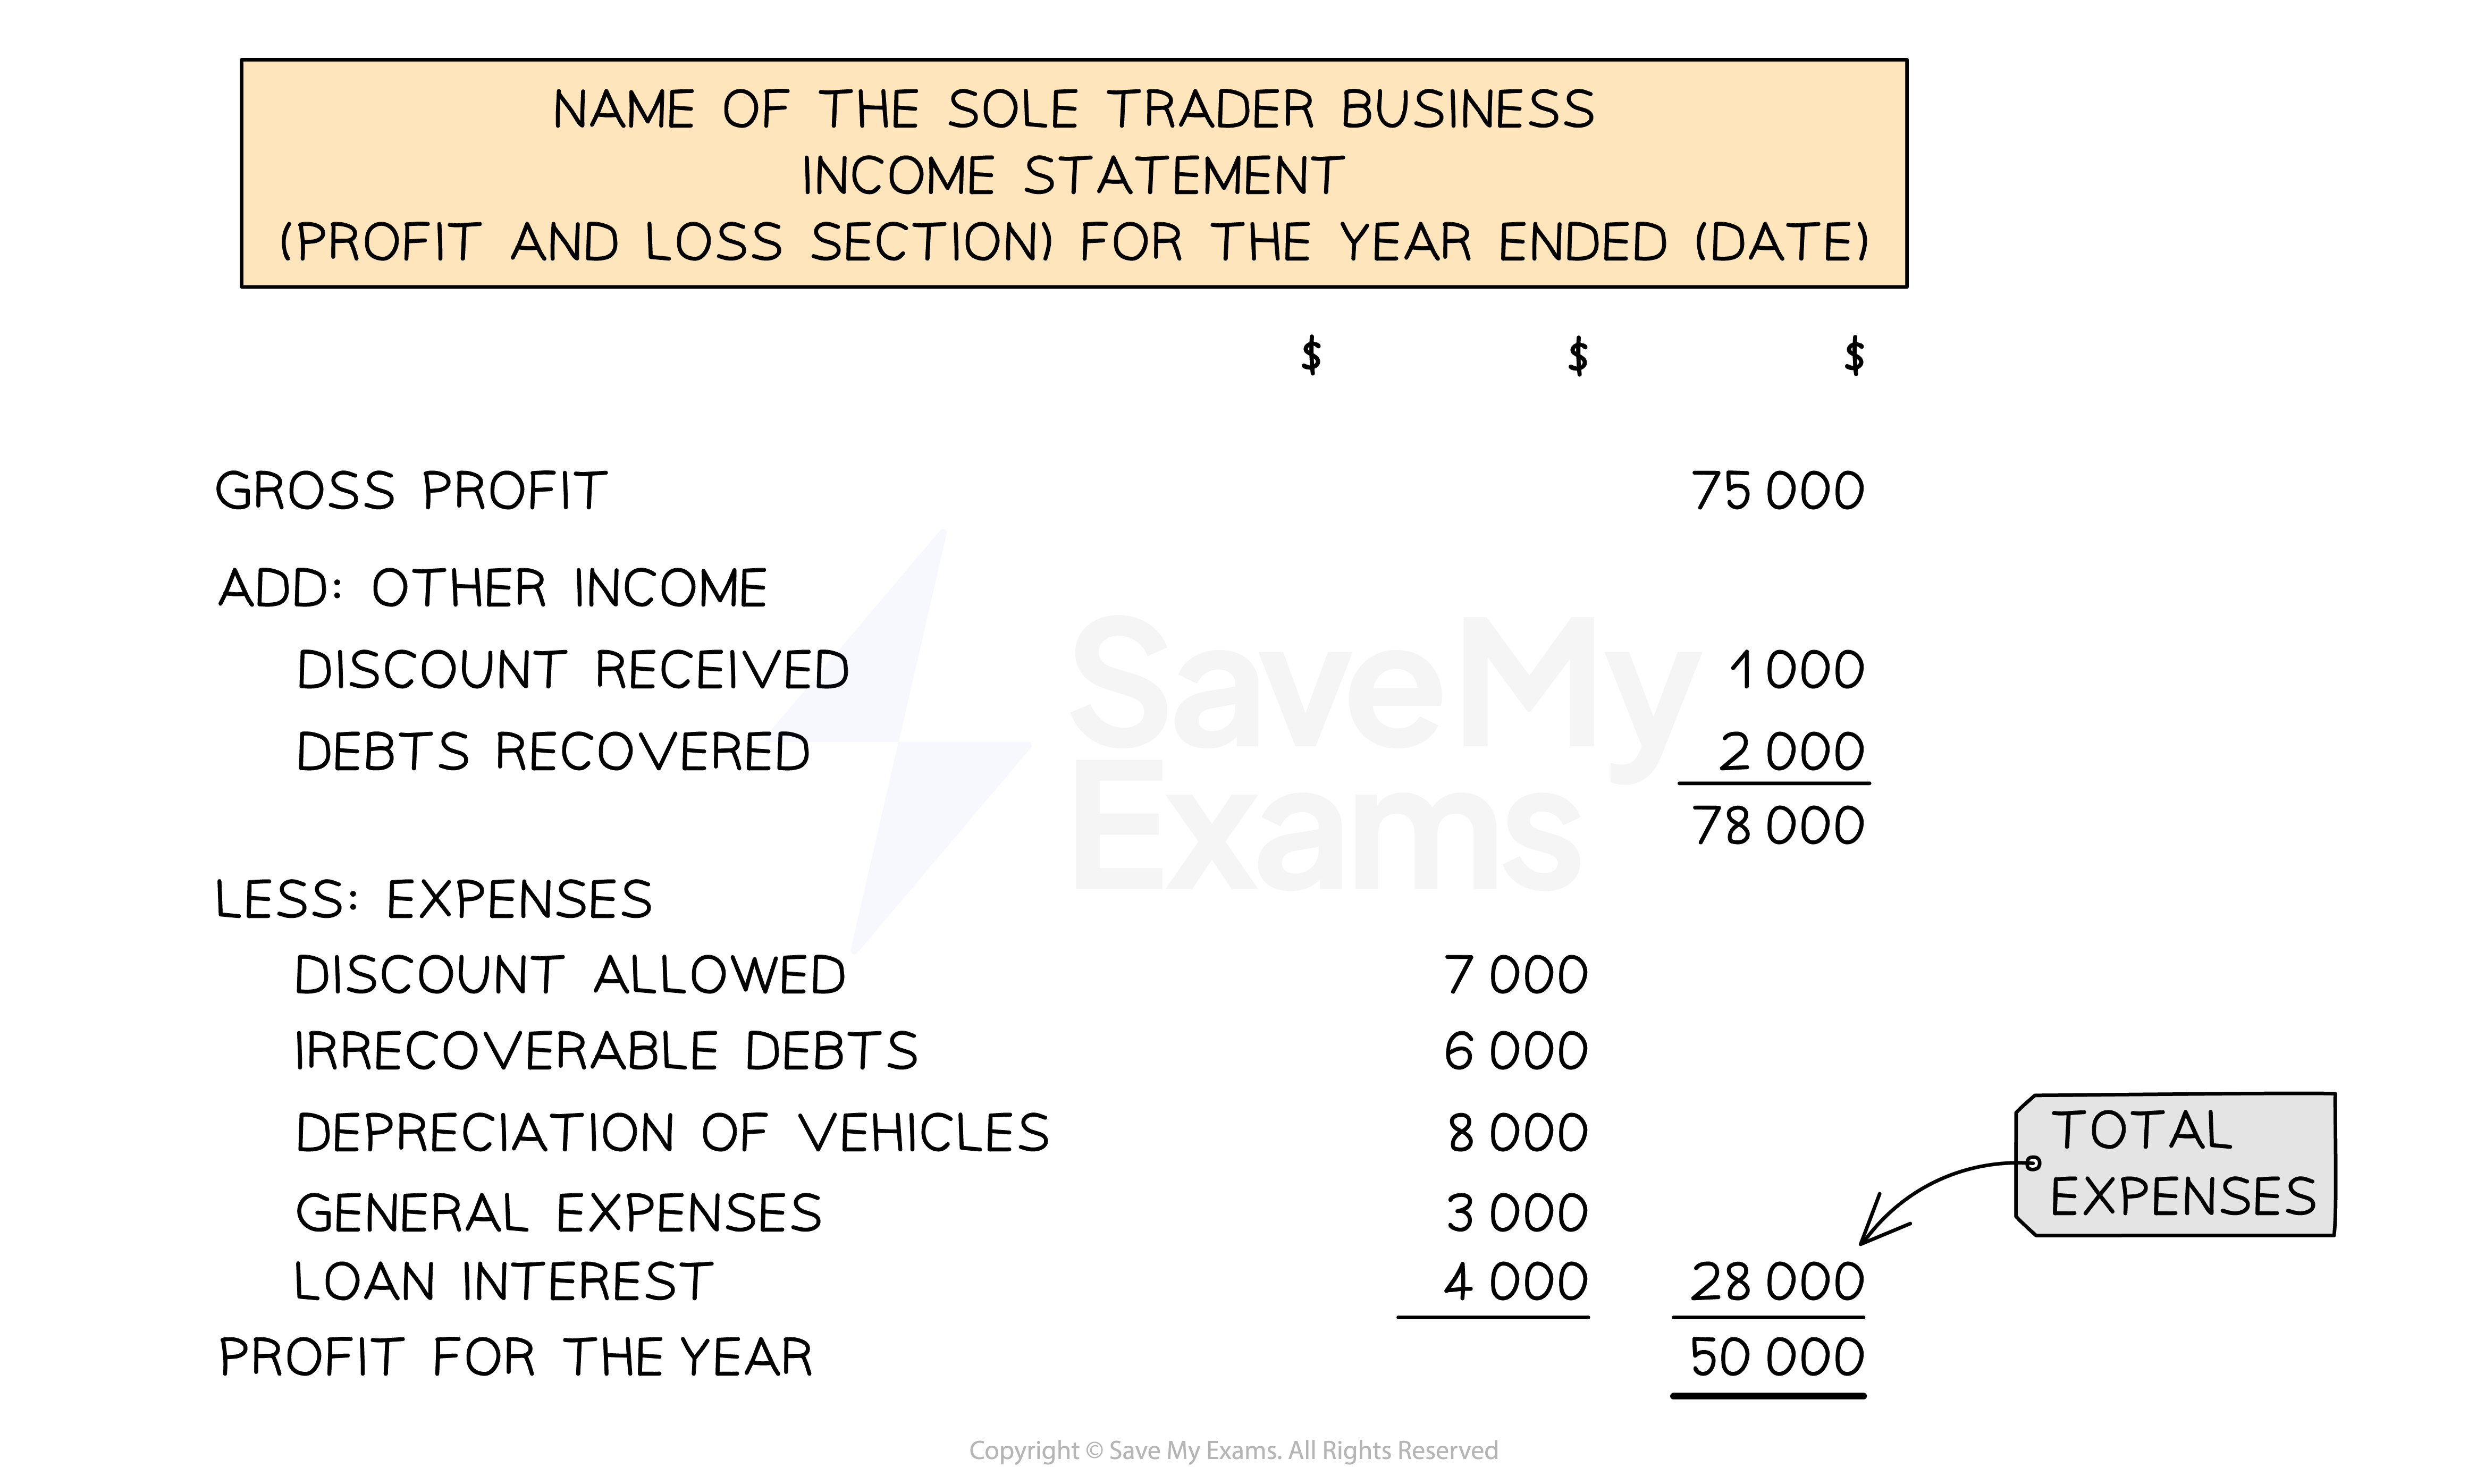
STEP 1
Put the gross profit in the far right columnSTEP 2
Total up any other incomes which increase the profit for the year such asDiscount received
Other income received
Recovery of irrecoverable debts
Profit on sale of non-current asset
STEP 3
Total up any other expenses which decrease the profit for the year such asDiscount allowed
Carriage outwards
Irrecoverable debts written off
Depreciation of non-current assets
Loss on sale of non-current assets
Sundry expenses
Other expenses
STEP 4
Calculate the profit or loss for the yearGross profit
Add other income
Less other expenses
If the final value is a negative
Put brackets around the value
This means it is a loss not a profit
E.g. (500) represents a loss of $500
What is operating profit?
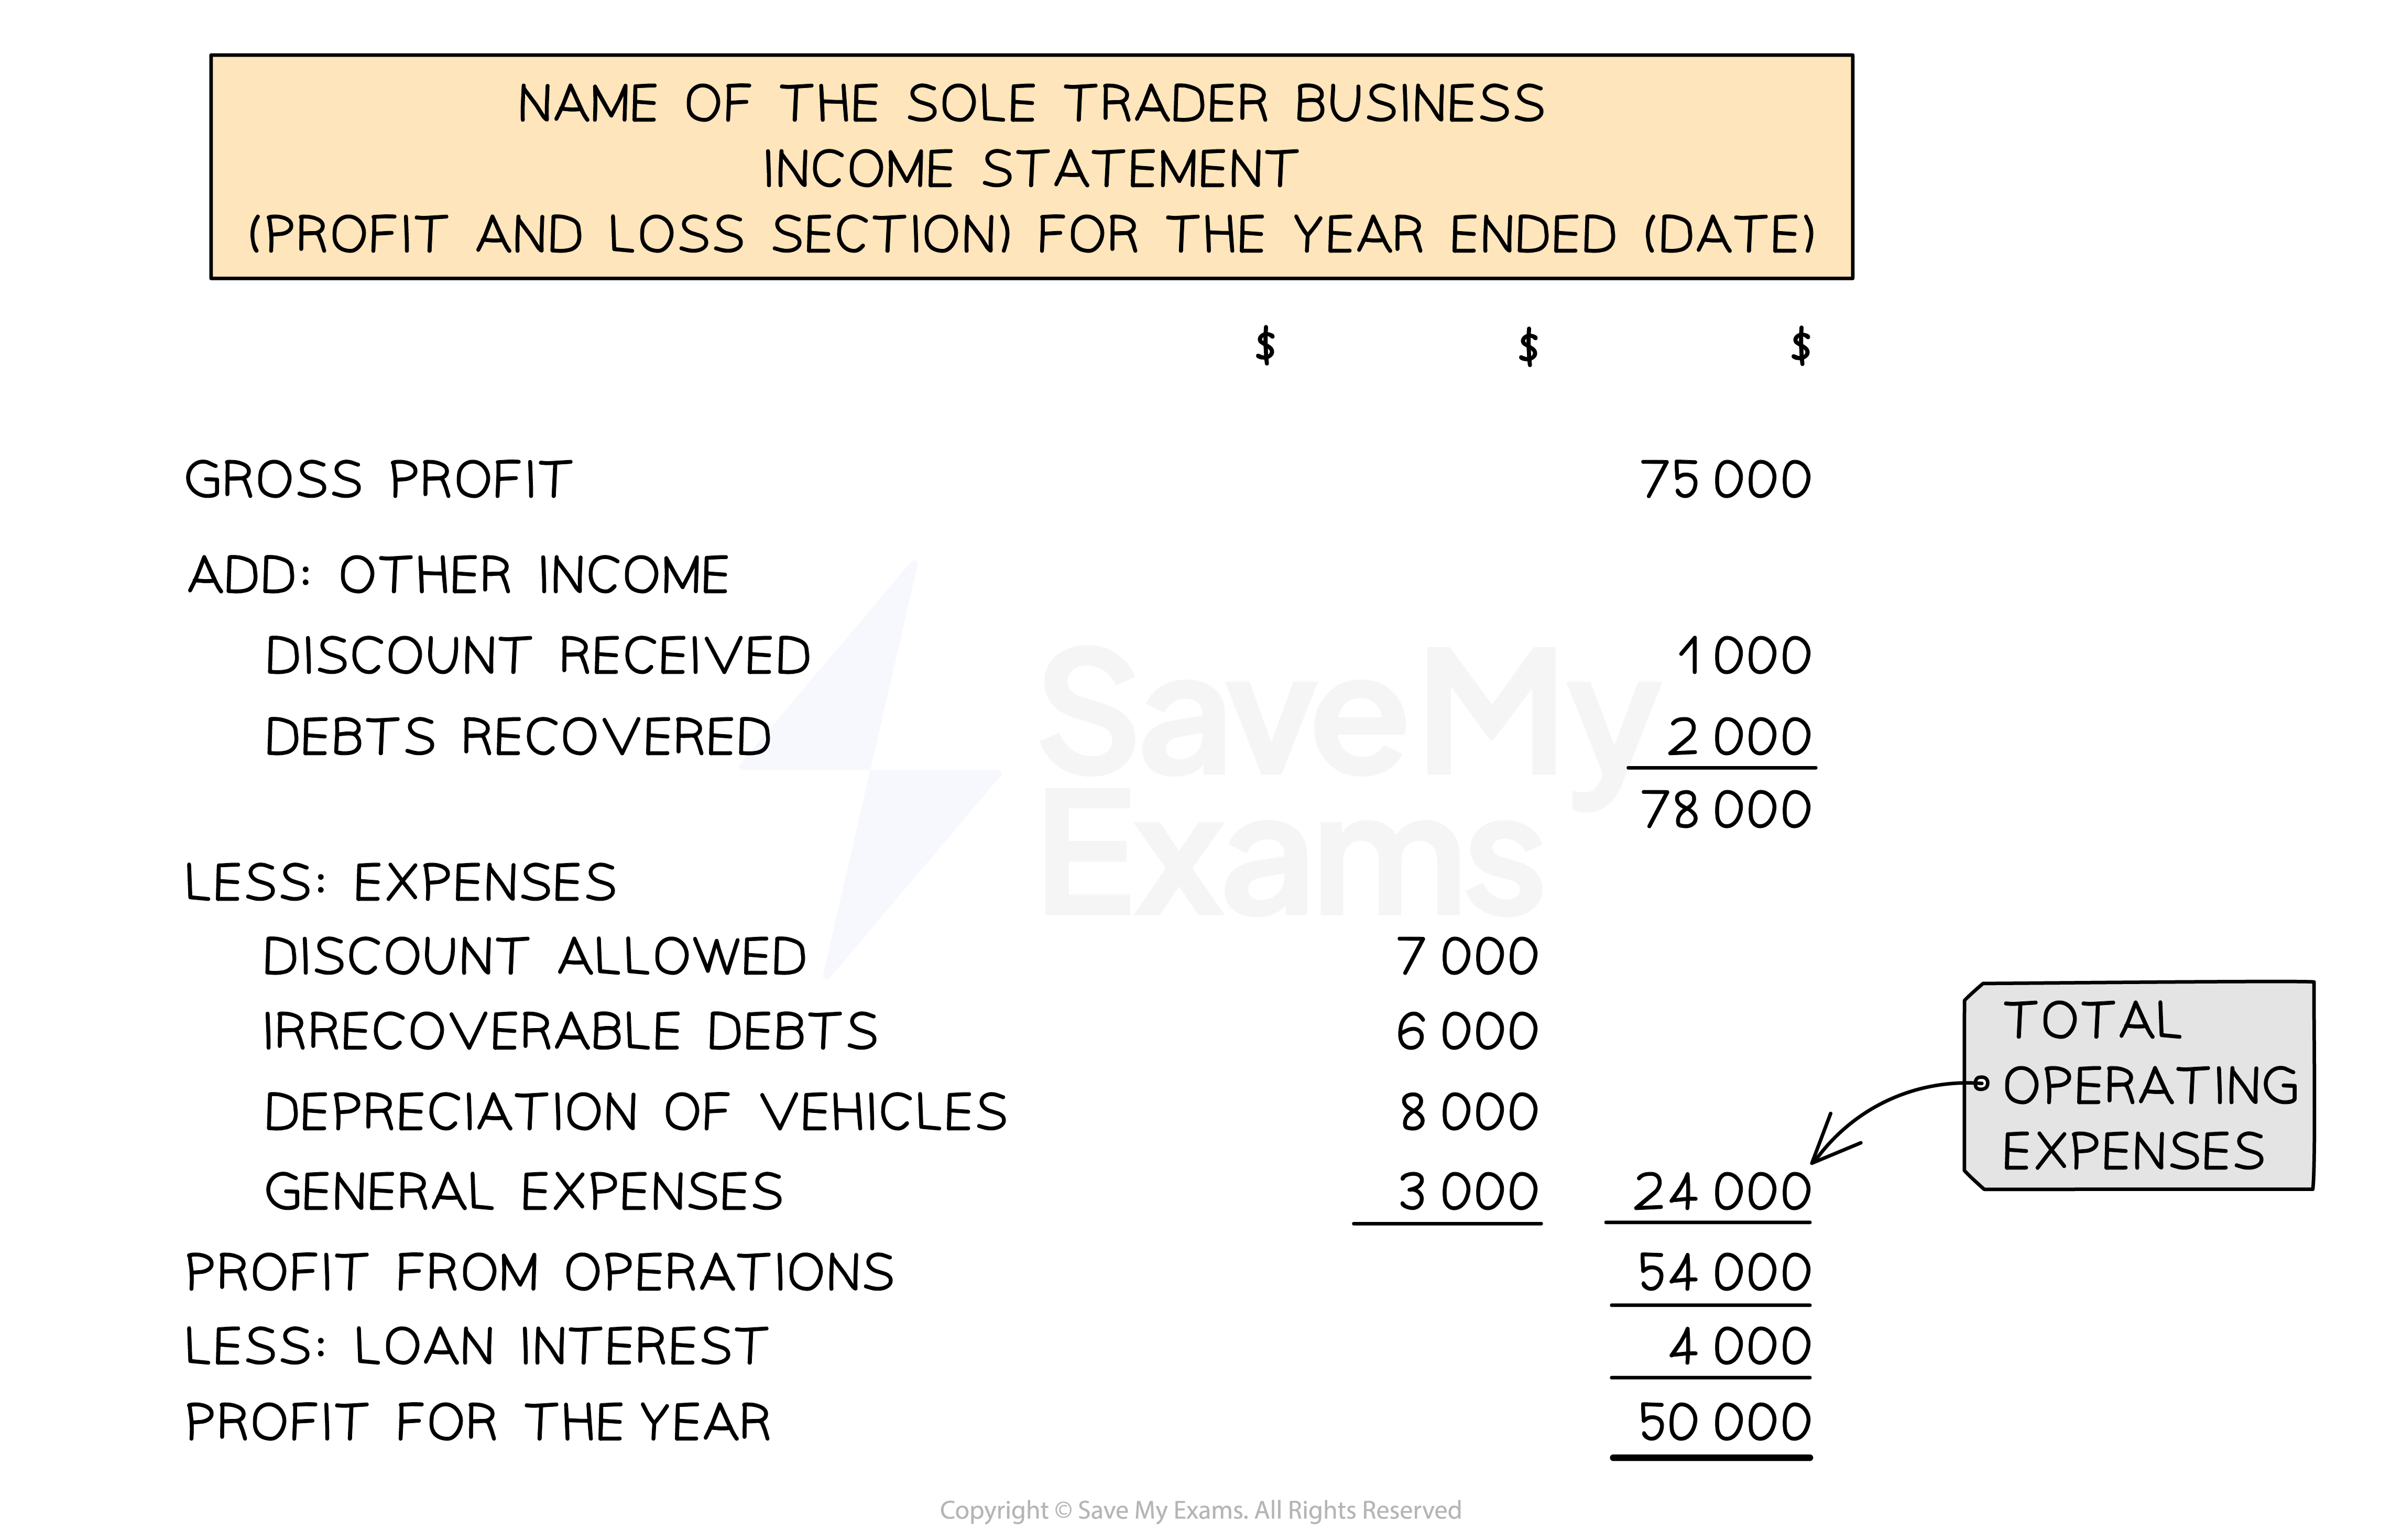
Operating profit is also known as profit from operations
It is the profit for the year before subtracting the loan interest
Some businesses show this in the profit and loss section of their income statement
If a business does not have finance costs then profit from operations is the same as profit for the year
How is the income statement of a trading business created?
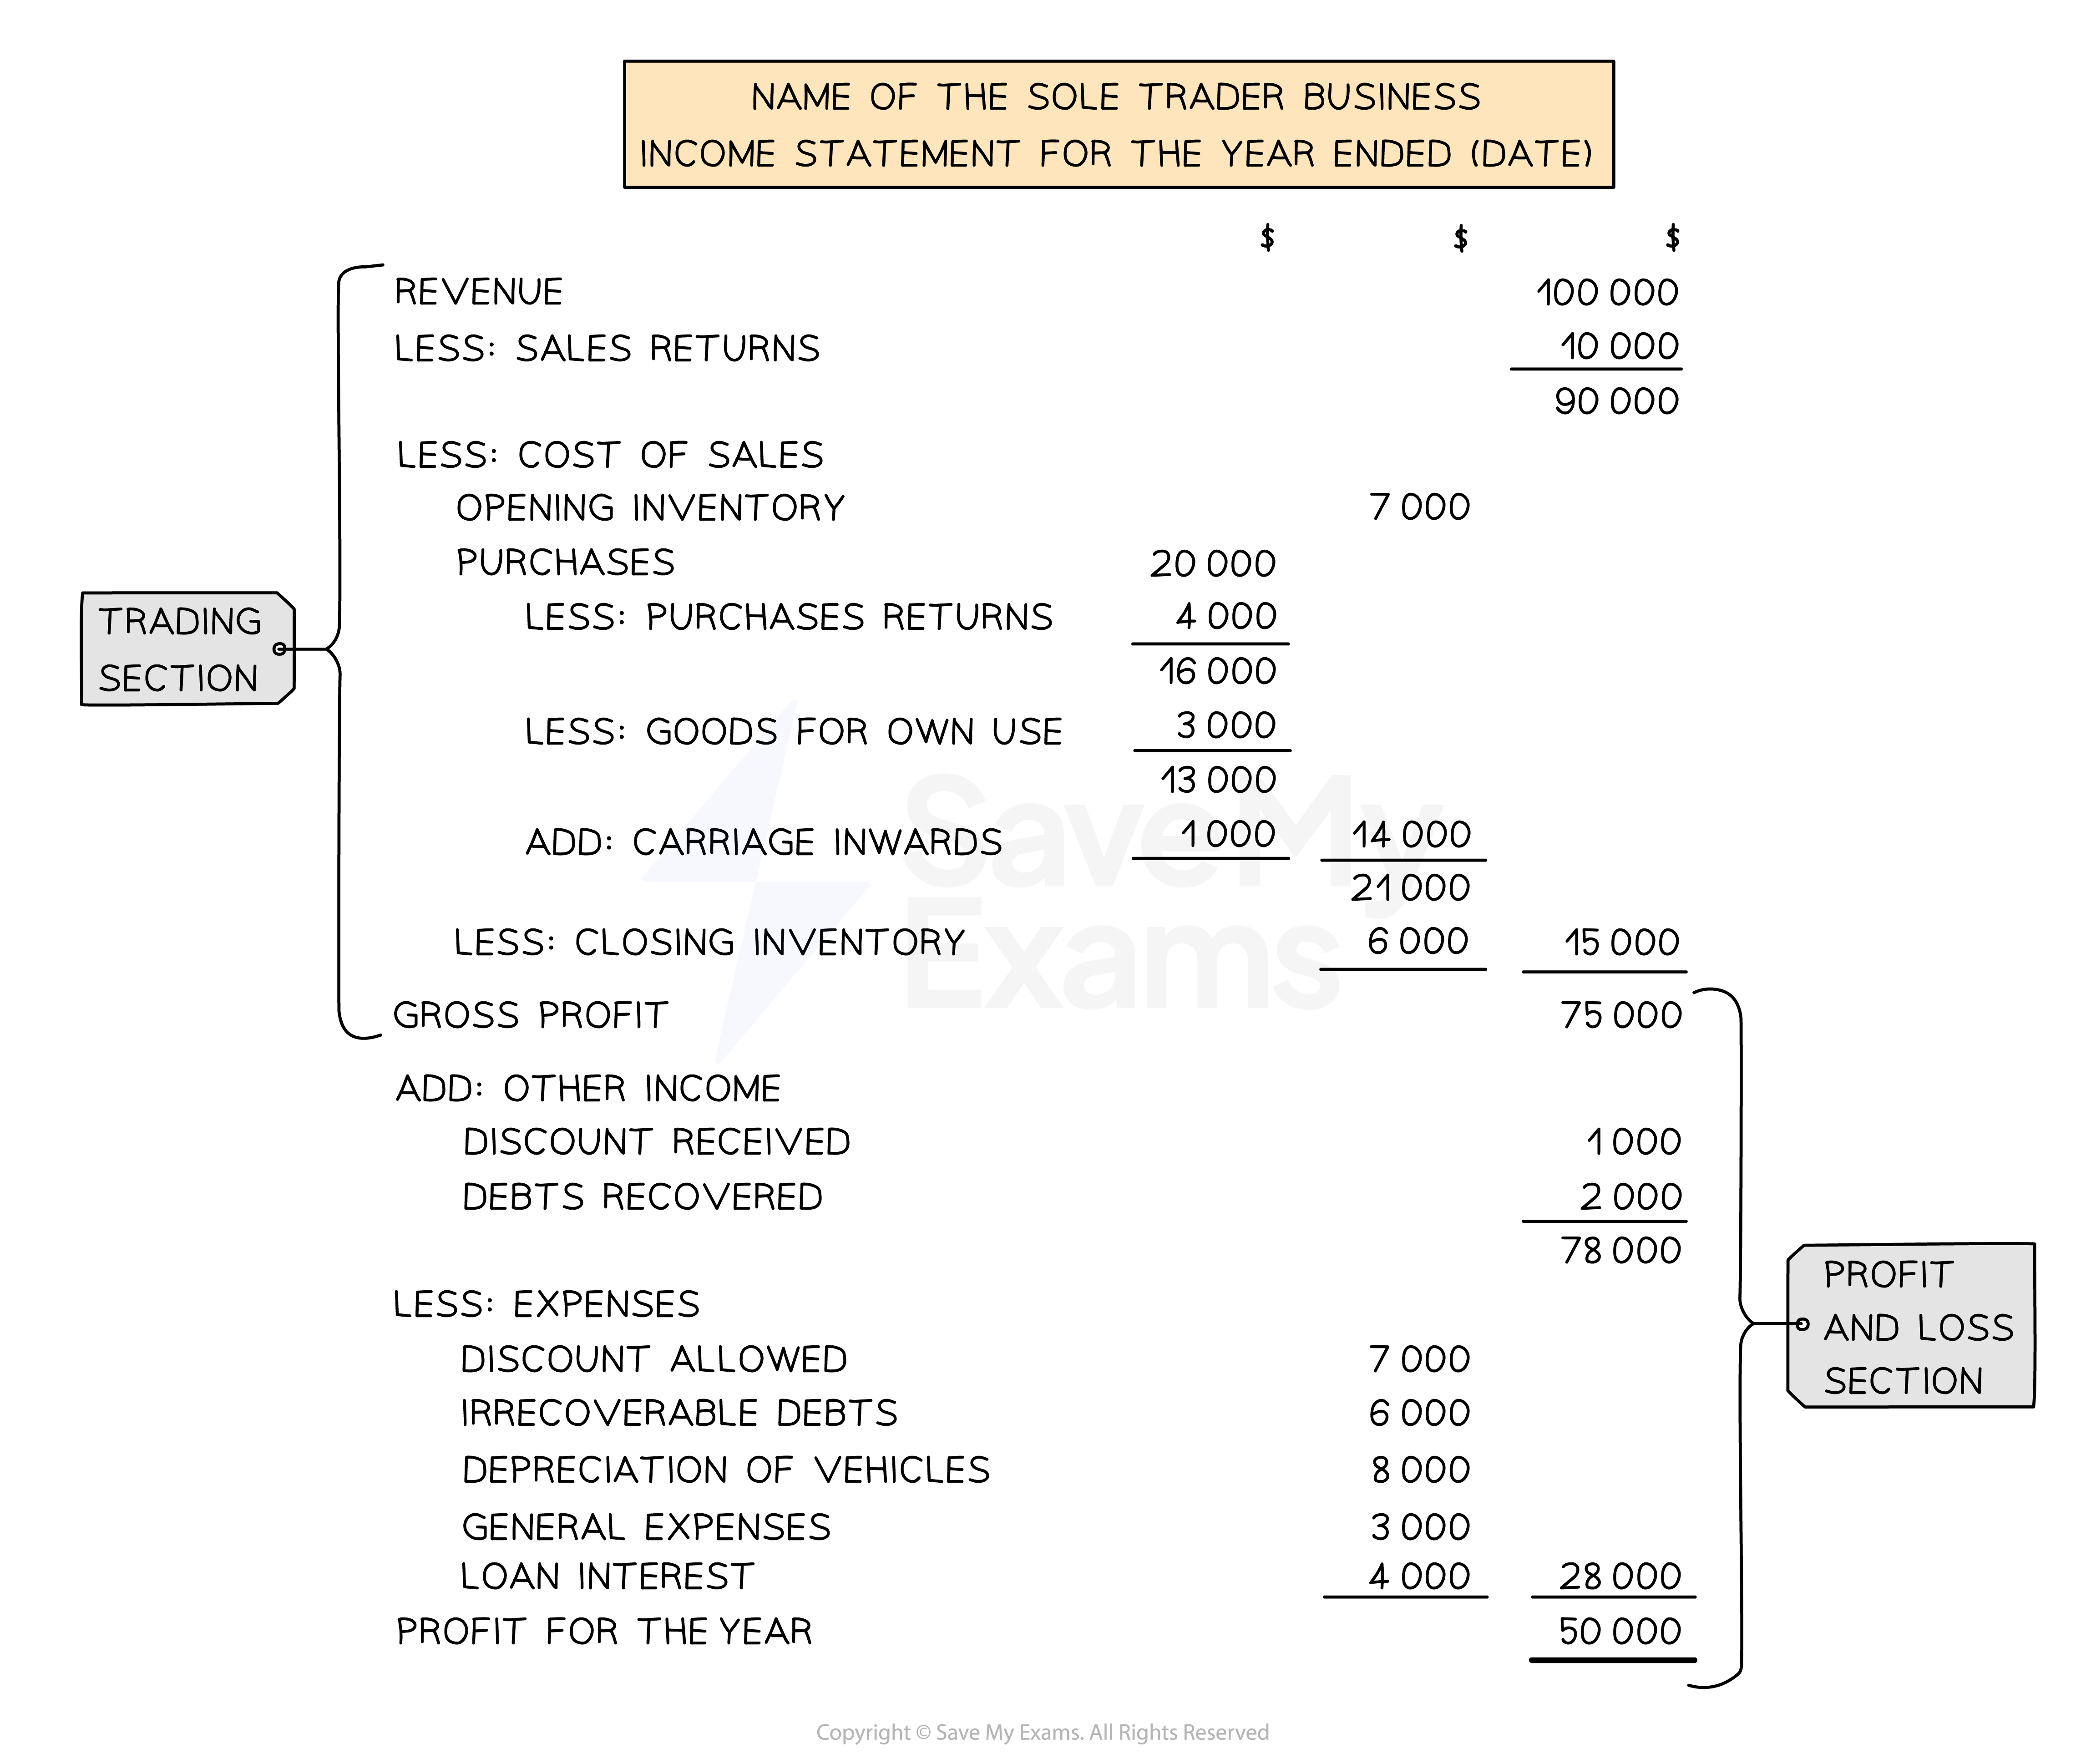
The income statement of a trading business contains both the
Trading section
Profit and loss section
The gross profit links the two sections together
You do not need to state this value twice
Income statement for service businesses
Income statement for service businesses
How is the income statement of a service business created?
The income statement of a service business does not have a trading section
Because they do not buy or sell goods
Therefore there will not be a gross profit
The income statement for a service business only contains the profit and loss section
Therefore the income statement will start with the income received
How do I complete an income statement for a service business?
STEP 1
Total up any income such as:Commission
Rent
Other income received
STEP 2
Total up any expenses such as:Wages
General expenses
Operating expenses
STEP 3
Calculate the profit or loss for the yearThe total income minus the total expenses