StudyDeck

The Nature of Business Activity

Exam code: 7115
Written by: Ashika|Reviewed by: Caroline Carroll|Updated 2 July 2026

Factors of production

Factors of production

  • Factors of production are the resources used to produce goods and services

    • They include land, labour, capital and enterprise
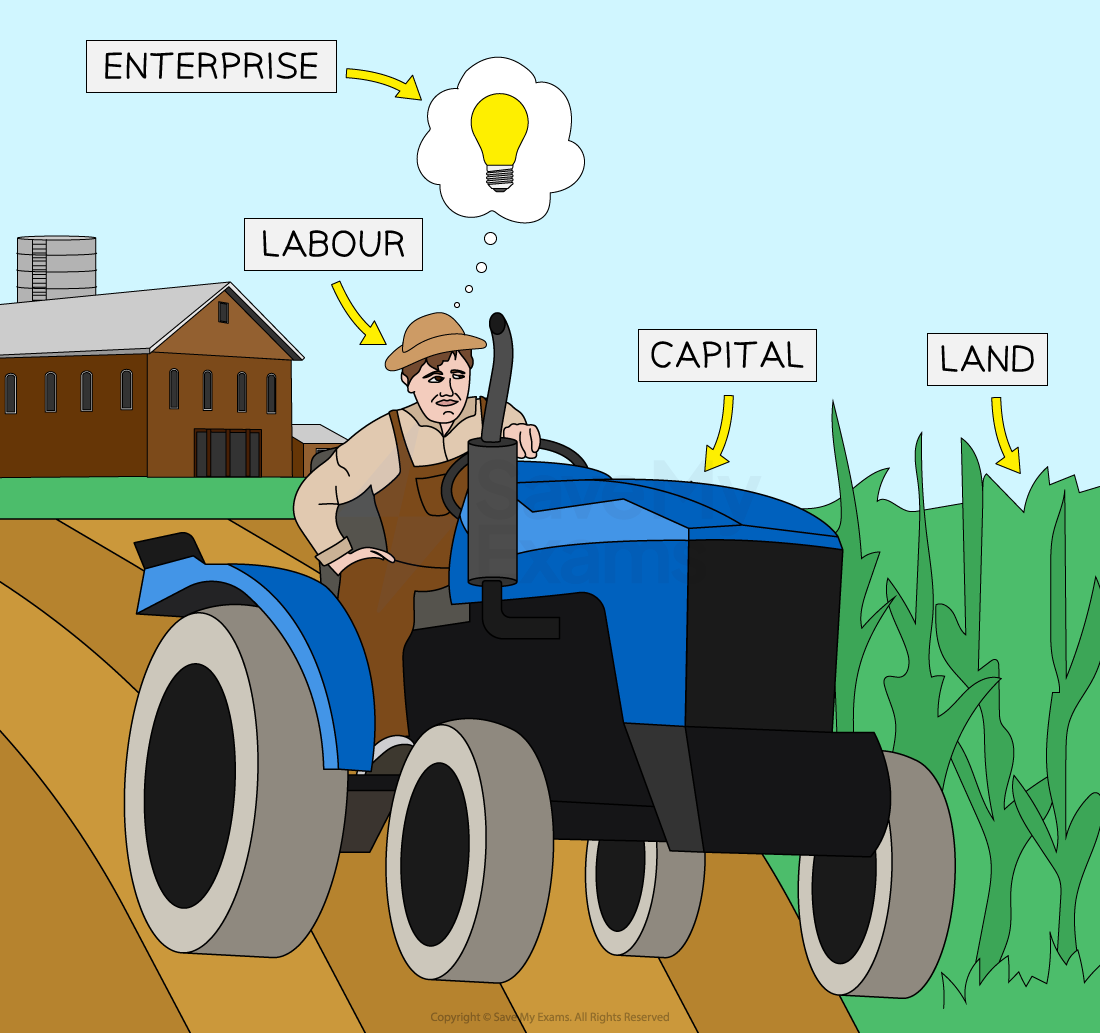
Farmer on blue tractor, with factory, crops, and thought bubble with lightbulb, labelled as enterprise, labour, capital, and land.
The four factors of production are land, capital, labour and enterprise
  • The production of any good or service requires the use of a combination of all four factors of production

    • Goods are physical objects that can be touched (tangible), e.g., a mobile phone

    • Services are actions or activities that one person performs for another (intangible), e.g., a manicure or car wash

Explanation of the four factors of production

Land

Capital

  • Non-man-made natural resources available for production

  • Some countries have a vast amount of a particular natural resource, so are able to specialise in its production

    • For example, Kuwait specialises in the product of oil which accounts for 95% of its exports

  • Capital is any man-made resource that is used to produce goods and services

  • Examples include tools, buildings, machines and computers

Labour

Enterprise

  • The human input into the production process, labour involves mental or physical effort

  • Not all labour is of the same quality

    • It can be skilled or unskilled

    • Some workers are more productive than others because of their education, training and experience

  • Enterprise involves taking risks in setting up or running a firm

  • An entrepreneur decides on the combination of the factors of production necessary to produce goods and services with the aim of generating profit

Adding value

Adding value

  • Adding value is the process of taking raw materials and using them in such a way that the end product created is worth more than the cost to make it

  • It is therefore the difference between the price charged to the customer and the cost of inputs required to create the product or service

    • For example, customers are prepared to pay more for potatoes when they are packaged as oven chips than they would be willing to pay for a bag of potatoes

  • The greater the added value, the more successful the business is likely to be and the higher their profits

  • Product and marketing teams explore ways to increase added value
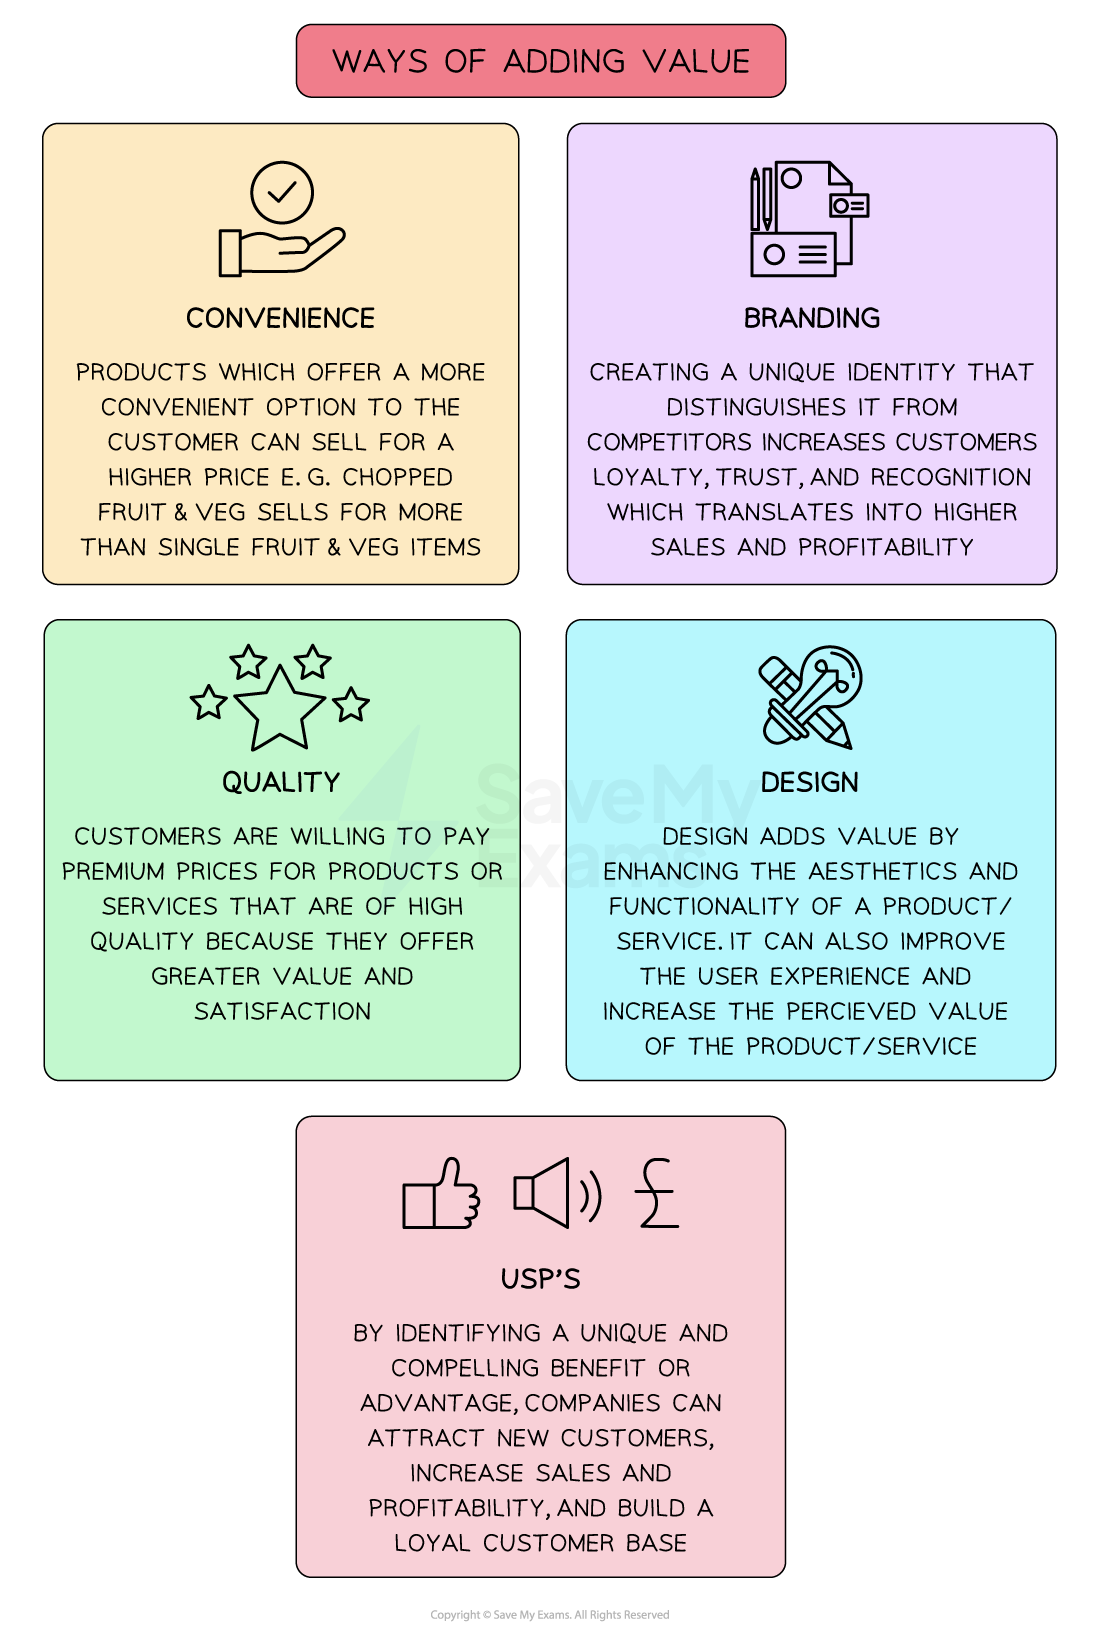
Infographic on ways to add value: convenience, branding, quality, design, and USPs, each with icons and descriptions in coloured boxes.
Some of the methods of adding value allow for product differentiation, which allows the business to charge a higher selling price

Examples of added value

Method

Example

Branding

  • Apple has built a brand that many customers believe is superior to other brands

    • They have achieved this through the use of quality materials, innovative design and good marketing

    • This branding allows the firm to charge a higher price for its products, thus increasing the added value

Convenience

  • Persil initially provided a bottle of dishwashing liquid for dishwashing machine use

    • This resulted in spillage as customers added the liquid to their machines, so Persil then created tablets

    • The tablets offered a much more convenient option and Persil was able to charge a higher selling price for them

Quality

  • Jo Malone perfume products are well known for their beautiful packaging, which creates an exciting opening experience for the customer

    • This allows the firm to charge a higher price for its products, thus increasing the added value

Unique selling points (USPs)

  • MoonPig birthday cards can be completely customised (size, colour, design etc.) and the level of customisation has helped them gain a competitive advantage

    • This customisation allows the firm to charge a higher price for its cards, thus increasing the added value

Design

  • Samsung Galaxy Watch 5 has robust health tracking tools built into it, along with an amazing screen, which has helped it gain a competitive advantage

    • These features allow the firm to charge a higher price for its products, thus increasing the added value

Opportunity cost

Opportunity cost

  • Opportunity cost is the loss of the next best alternative when making a decision

  • Businesses thrive when they are able to meet customer needs and wants

    • Needs are essential, e.g. shelter or food

    • Wants are desires which are not essential e.g Nike trainers

  • Due to the problem of scarcity, there is a basic economic problem

    • Choices have to be made by producers, consumers, workers and governments about the most efficient use of resources

  • There is an opportunity cost in the allocation of resources

    • When a consumer chooses to purchase a new phone, they may be unable to purchase new jeans

      • The jeans represent the loss of the next best alternative (the opportunity cost)

    • When a producer decides to allocate all of their resources to producing electric vehicles, they may be unable to produce petrol vehicles

      • The petrol vehicles represent the loss of the next best alternative (the opportunity cost)

    • When a government decides to provide free school meals to all primary students in the country, they may be unable to fund rural libraries, which may have to close

      • The libraries represent the loss of the next best alternative (opportunity cost)