Solutions to Market Failure: Maximum & Minimum Prices
Intervention to address market failure
Intervention to address market failure
Four of the most commonly used methods to address market failure in markets are
maximum prices
minimum prices
indirect taxation
subsidies
Additional methods of intervention include regulation, nationalisation, privatisation, and government (state) provision of public goods
Maximum prices
Maximum prices
A maximum price is set by the government below the existing free market equilibrium price and sellers cannot legally sell the good/service at a higher price
Governments will often use maximum prices in order to help consumers.
Sometimes they are used for long periods of time e.g. housing rental markets.
Other times they are short-term solutions to unusual price increases e.g. petrol
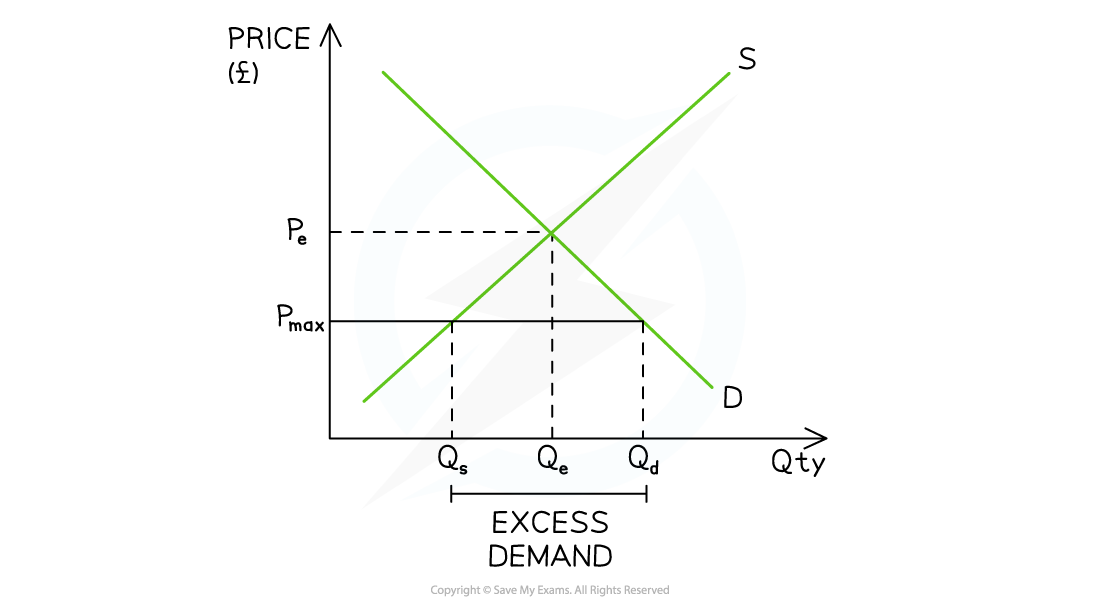
Diagram analysis
The initial market equilibrium is at PeQe
A maximum price is imposed at Pmax
The lower price reduces the incentive to supply and there is a contraction in QS from Qe → Qs
The lower price increases the incentive to consume and there is an extension in QD from Qe → Qd
This creates a condition of excess demand equal to QsQd
Evaluating the use of maximum prices
Advantages | Disadvantages |
|---|---|
|
|
Minimum prices
Minimum prices
A minimum price is set by the government above the existing free market equilibrium price and sellers cannot legally sell the good or service at a lower price
Governments will often use minimum prices in order to help producers or to decrease consumption of a demerit good such as alcohol
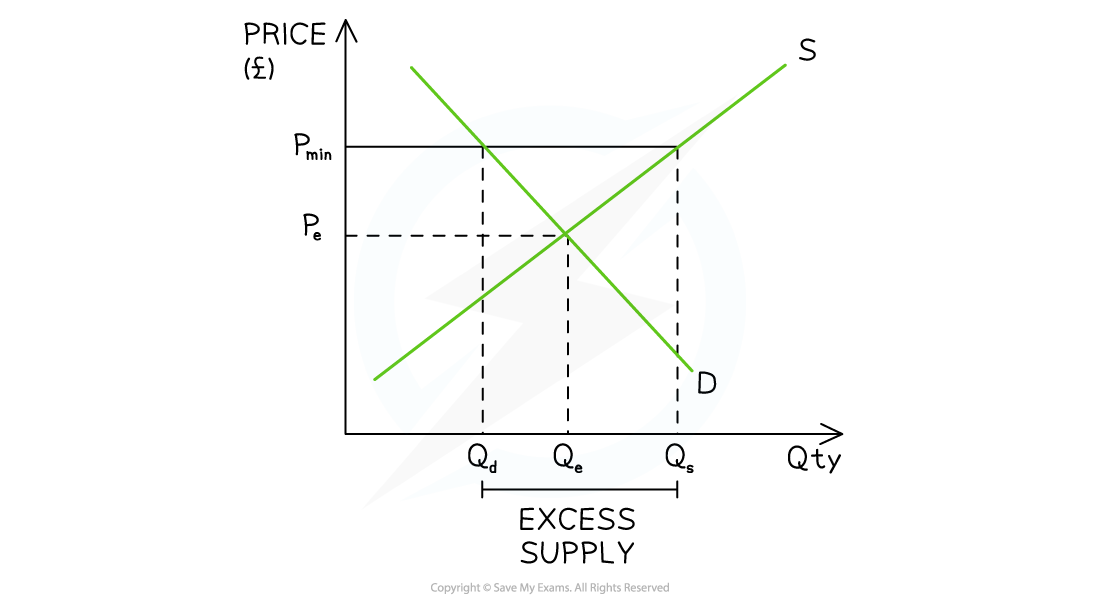
Diagram analysis
The initial market equilibrium is at PeQe
A minimum price is imposed at Pmin
The higher price increases the incentive to supply and there is an extension in QS from Qe → Qs
The higher price decreases the incentive to consume and there is a contraction in QD from Qe → Qd
This creates a condition of excess supply QdQs
Evaluating the use of minimum prices in product markets
Advantages | Disadvantages |
|---|---|
|
|
Minimum prices in labour markets
Minimum prices are also used in the labour market to protect workers from wage exploitation
These are called national minimum wages
A national minimum wage (NMW) is a legally imposed wage level that employers must pay their workers
It is set above the market rate
The minimum wage per hour varies based on age
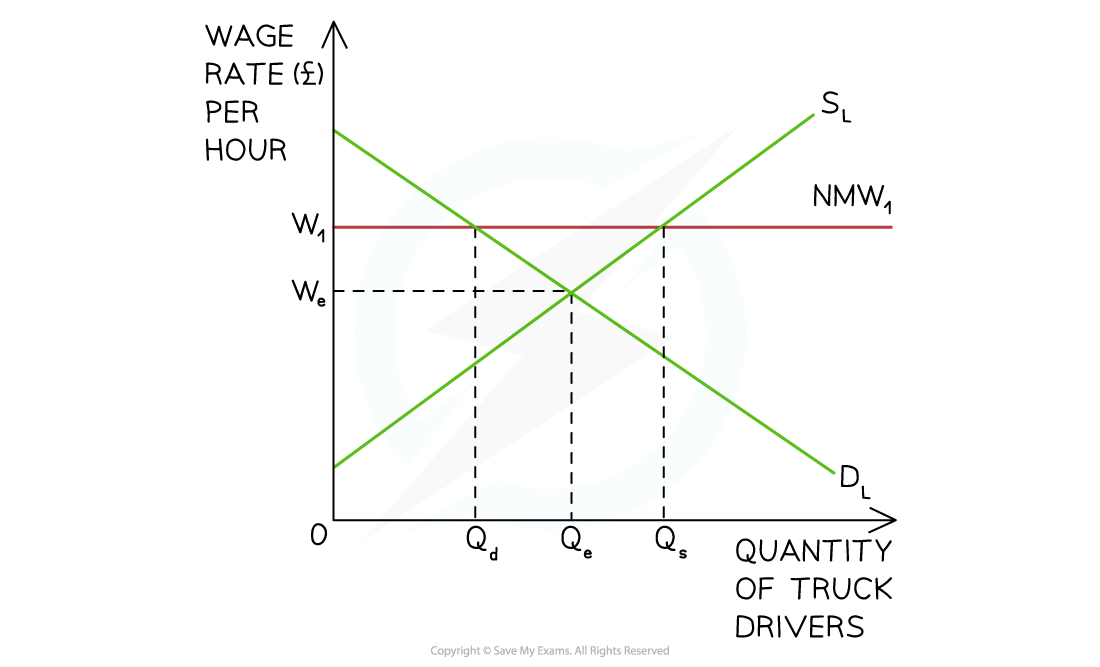
Diagram analysis
The demand for labour (DL) represents the demand for workers by firms
The supply of labour (SL) represents the supply of labour by workers
The market equilibrium wage and quantity for truck drivers in the UK is seen at WeQe
The UK government imposes a national minimum wage (NMW) at W1
Incentivised by higher wages, the supply of labour increases from Qe to Qs
Facing higher production costs, the demand for labour by firms decreases from Qe to Qd
This means that at a wage rate of W1 there is excess supply of labour and the potential for unemployment equal to QdQs
Evaluating the use of a minimum wage in labour markets
Advantages | Disadvantages |
|---|---|
|
|